
Business Plan for Growth That Scales SMEs to 7 Figures
You've got a healthy order book, a team that's busy, and a turnover figure that looks close to the next milestone. Yet the bank balance still feels tight. You're approving another hire before the last one is fully productive, accepting work at yesterday's prices, and checking Xero only when the VAT return or payroll deadline forces the issue.
That isn't a growth strategy. It's a business absorbing more activity without proving that the activity creates cash, margin, or capacity. A properly designed business plan for growth turns ambition into an operating model. It connects sales, delivery, people, technology, finance, and decision-making so you can build a larger business without building a more fragile one.
Why Most SME Growth Plans Stall Before Scale
A typical plateau begins innocently. The owner of a Central Scotland consultancy wins several attractive contracts, adds subcontractors to handle delivery, and sees revenue move upwards. The work looks successful from the outside, but invoices go out late, project margins vary, and the owner remains the person who approves every quote, solves every service issue, and reviews every payment.
The business has grown in volume, not control. A bank-ready document might describe an ambitious sales target, but it won't fix a weak handover process or reveal that a profitable-looking contract consumes too many unpaid hours. Your plan must answer a harder question: what must change inside the business for growth to produce dependable profit and cash?
Durability comes before acceleration
The UK survival hurdle is substantial. The latest ONS business demography and survival data reports a five-year survival rate of 38.4% for businesses born in 2019, so fewer than four in ten were still active five years later. The South West recorded the highest five-year survival rate at 43.5%, while the West Midlands recorded the lowest at 30.6%, showing that local conditions can affect outcomes materially.
Those figures aren't a reason to avoid growth. They're a reason to sequence it. Cashflow control, operational resilience, and phased expansion should sit inside the plan before you commit to larger payroll, premises, stock, or marketing costs. The same ONS release records business deaths falling from 324,000 in 2019 to 316,000 in 2020, with the death rate easing from 10.8% to 10.5%. Treat these as context, not comfort. A business can still fail during a period of sales growth if cash timing and operational control are poor.
Replace the document with a management rhythm
The productivity evidence points to management quality and digital adoption as practical growth levers. The UK government's small-business strategy evidence annex states that 67.7% of firms had labour productivity below the mean in 2022. It also cites leadership and management investment, alongside digital technology adoption, as clear drivers of firm-level productivity. An increase of 0.1 points in management scores was associated with a 9.6% increase in productivity, according to the historical evidence referenced in that annex.
Your plan should therefore become a monthly management pack and a quarterly decision meeting. Use Xero for reliable financial records, connect relevant apps, assign owners to KPIs, and record decisions rather than relying on memory. The outcome is practical: more time, because the owner stops being the operational bottleneck; more money, because pricing, margin, and cash conversion receive attention; and a clearer mind, because decisions come from current information.
Practical rule: If the plan doesn't change what you review, who owns it, or what you do next, it's not an operating model. It's paperwork.
Defining Growth Objectives and Market Opportunity
A turnover target is not a growth objective until you can explain where the revenue will come from, what it will cost to deliver, and why the business can capture it. Start by choosing the commercial outcome that matters most. That may be revenue, operating profit, recurring income, market share, owner capacity, or delivery capacity. Don't combine every ambition into one vague statement.
Write the objective in a form that creates decisions:
- Revenue-led: Increase sales by deepening existing client relationships or entering a defined segment.
- Profit-led: Improve gross margin by changing prices, service mix, supplier terms, or delivery methods.
- Capacity-led: Increase delivery capability without allowing quality or owner workload to deteriorate.
- Value-led: Build recurring contracts, stronger retention, or transferable processes that improve the eventual value of the business.
The right objective determines the evidence you need. A profit-led plan must analyse contribution by service, client, and delivery channel. A recurring-income strategy needs evidence of retention, onboarding capacity, and customer demand for ongoing support.
Test the market before building the forecast
The structure of a business plan should follow your commercial logic, not a template's headings. Define your best-fit customer narrowly enough to make the proposition useful. Identify their urgent problem, the alternatives they use now, the person who approves the purchase, and the reason they would choose you instead of a cheaper or more familiar supplier.
Then test four assumptions:
- Demand: Which customer group has a current reason to buy?
- Positioning: What do you do differently, and can you prove it?
- Pricing: Does the price reflect the value delivered and the cost of reliable fulfilment?
- Reach: Can your chosen sales channels reach enough suitable prospects without consuming excessive management time?
A service business in Central Scotland might decide to focus on employers who need specialist compliance support rather than market every service to every local business. Its plan would examine referral sources, competitor response times, client buying concerns, and the delivery hours available. It might test a packaged service with a defined scope before investing in a larger team.
Keep regional assumptions grounded
Market opportunity isn't uniform across the UK. Local competition, transport, sector concentration, recruitment conditions, and customer spending power affect how quickly a proposition can scale. A plan aimed at clients in Alloa, Stirling, Falkirk, Glasgow, or remote markets should state which assumptions depend on geography and which can travel nationally.
Avoid quoting a huge total market and treating it as attainable demand. Build the opportunity from a realistic customer list, an identifiable buying trigger, a credible conversion process, and the capacity to deliver. Your objective becomes stronger when a sceptical reader can challenge each assumption and you can show what evidence would confirm or reject it.
Aligning Sales Marketing and Operational Capacity
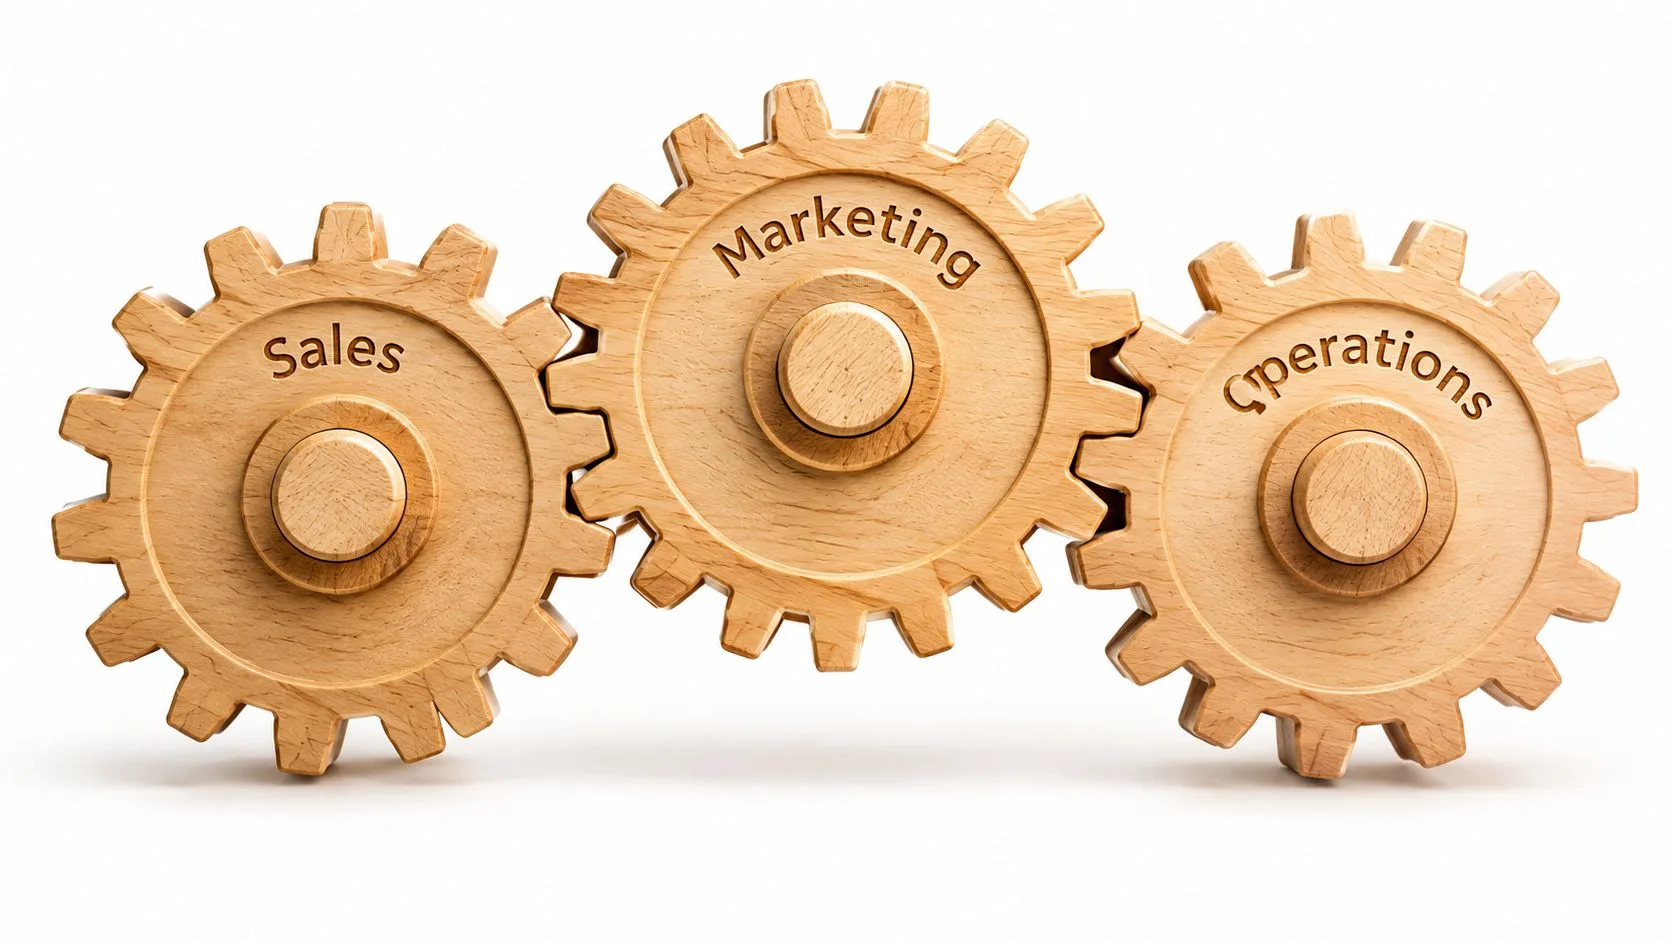
Sales, marketing, and operations are one system. Marketing creates attention, sales converts suitable demand, and operations delivers what was promised. If one part runs faster than the others, the business pays for the imbalance through wasted leads, rushed work, discounting, rework, or late invoicing.
Start with the commercial engine
Your sales plan should show how a prospect becomes collected cash. Map the journey from target account to enquiry, qualification, proposal, accepted work, delivery, invoice, and payment. Assign responsibility at each stage and define the information required before the next handover. A pipeline full of unqualified opportunities isn't evidence of growth. It's a list of possible distractions.
Pricing deserves its own line of scrutiny. Record the price, direct delivery cost, expected time, subcontractor exposure, payment terms, and likely scope changes for each core offer. If a proposal needs discounting to win, record the reason and test whether the resulting margin still supports the company's overhead and investment plans.
Retention matters because repeat work reduces the need to replace every client through new acquisition. Build account reviews, renewal dates, service feedback, and cross-sell opportunities into the process. Don't confuse a friendly relationship with a controlled retention strategy.
Stress-test delivery before increasing demand
Operations should answer practical questions:
- How much work can the current team complete without overtime becoming normal?
- Which tasks require a scarce skill or the owner's direct involvement?
- Where do suppliers create lead-time or quality risk?
- Which process fails first when demand rises?
- What must be documented before a new employee or subcontractor starts?
- When will a new hire become productive enough to justify the cost?
Sequence investment instead of hiring on instinct. First remove avoidable manual work, then improve the process, then decide whether outsourcing, automation, or recruitment is appropriate. Xero can provide the financial record, while connected tools can help track proposals, projects, time, expenses, and payment status. The important outcome is a joined-up view from pipeline to cash, not a collection of disconnected dashboards.
Businesses with complex handoffs may benefit from specialist guidance on RevOps consulting for scalable systems, particularly when sales data, delivery information, and finance records sit in separate systems. You don't need an elaborate technology stack. You do need consistent definitions and clear ownership.
Protect service quality while you scale
Marketing should never promise a delivery experience that operations can't provide. If response times, onboarding, reporting, or technical support will change as volume rises, state that in the plan and fund the required capacity before the campaign launches.
Use leading indicators, not just completed sales. A rising proposal count with flat delivery capacity should trigger a decision. So should increasing work in progress, delayed invoicing, rising subcontractor reliance, or a growing queue of unresolved client issues. The strongest plan makes these constraints visible early enough for the owner to act.
Building Financial Forecasts KPIs and Scenario Plans
Your financial model should tell you whether the growth strategy is affordable, not merely whether the sales target looks attractive. Build three linked forecasts: a profit and loss account, a cashflow forecast, and a balance sheet forecast. Each answers a different question.
The profit and loss forecast tests revenue, direct costs, overhead, and profit. The cashflow forecast shows when money arrives and leaves. The balance sheet exposes receivables, payables, VAT, debt, stock, and the funding required to support the operation. A business can report profit and still face a cash crisis if customers pay slowly while payroll, suppliers, and VAT fall due earlier.
Build the model from operating assumptions
Start with drivers rather than arbitrary totals. Use expected lead sources, sales conversion, average order value, delivery capacity, staff costs, supplier costs, payment terms, and planned investment. Separate committed costs from optional spending. Make every material assumption visible so you can change it when reality changes.
Model base, upside, and downside cases. The downside case should not be a theatrical collapse. It should reflect plausible pressure, such as slower conversion, delayed customer payment, higher delivery costs, or a recruitment delay. Then identify the trigger that moves you from one scenario to another and the action you'll take.
A Xero workflow can support this discipline:
- Reconcile bank accounts promptly and review unreconciled items.
- Use consistent invoice, customer, supplier, and tracking-category information.
- Produce monthly management accounts with comparisons to budget and prior periods.
- Review aged receivables and assign collection actions.
- Reconcile VAT and payroll liabilities to the cash forecast.
- Update the rolling forecast after each monthly review.
For a detailed model, use financial projections support that connects monthly profit and loss, cashflow, and balance sheet assumptions rather than treating each report separately.
Choose KPIs that change behaviour
A KPI earns its place when someone can act on it. Don't report a dozen measures because your software can produce them. Select indicators that expose commercial performance, delivery pressure, and cash timing.
| KPI Category | Example Metric | Target Cadence | Xero Workflow Tip |
|---|---|---|---|
| Pipeline | Qualified opportunities by stage | Monthly | Use consistent customer and tracking information, then compare pipeline movement with invoiced sales |
| Margin | Gross margin by service or project | Monthly | Use tracking categories and review direct costs against the related income |
| Cash conversion | Aged receivables and overdue invoices | Weekly or monthly | Review the aged receivables report and assign collection owners |
| Pricing | Average fee and discount approval | Monthly | Compare invoiced prices with the service or project category |
| Hiring | Payroll cost against productive revenue | Monthly | Review payroll journals alongside revenue and capacity assumptions |
| Tax timing | VAT and payroll liabilities due | Monthly | Reconcile liabilities to the cash forecast before approving discretionary spend |
Cash rule: Revenue creates a promise. Cash conversion pays the bills.
Run a monthly management meeting
Keep the meeting operational. Review actual results against forecast, explain material variances, check the next cash pinch point, and agree named actions with deadlines. Ask whether the forecast still reflects current sales, staffing, pricing, and payment behaviour.
Quarterly, revisit the assumptions rather than rolling the same forecast forward. If the business is winning lower-margin work, the answer may be a pricing or service-mix decision, not another marketing campaign. If sales are healthy but receivables are expanding, tighten terms and collection before adding headcount.
Funding Your Growth and Turning Capital Into Profit
Finance is useful only when the business can convert it into profitable capacity. The UK government's SME growth plan reports that just 1.5% of UK SMEs apply for bank loans, compared with up to 22% in major EU countries, and estimates that accelerating SME growth by one percentage point per year could add £320 billion to the UK economy by 2030. These figures come from the government's SME growth plan evidence, but the practical lesson is more important than the headline: many businesses don't build a funding strategy early enough.
Match the funding route to the asset
Retained profit suits measured investment where cash generation is reliable, but it can be too slow for a time-sensitive opportunity. A bank loan can fund a defined expansion, provided repayments remain affordable under the downside forecast. Asset finance may match equipment purchases more closely to the period in which the equipment generates income. Equity can support larger or riskier expansion, but it changes ownership and governance.
The Growth Guarantee Scheme may be relevant where a lender requires additional risk support. The British Business Bank reports that 69% of Growth Guarantee Scheme lending has gone to businesses outside London and the South East, while Scotland received £127.05 million across 766 facilities, according to its Growth Guarantee Scheme lending update. Access isn't automatic, and a strong plan still needs to demonstrate repayment capacity, management control, and a credible use of funds.
Use this decision test:
- Retained profit: Best for lower-risk investment with manageable timing.
- Term lending: Suitable for an identifiable asset or expansion with forecast repayment capacity.
- Asset finance: Useful when equipment directly supports delivery.
- Guarantee-backed lending: Worth exploring when the proposal is sound but security or lender risk appetite creates a barrier.
- Equity: Appropriate when the business needs patient capital and the owners accept shared control.
- Investor introductions: Consider curated investor connections only when equity fits the strategy, not because debt feels inconvenient.
Fund milestones, not hope
Release investment in stages. For example, approve initial spending to validate demand, then commit further funds when the business reaches agreed evidence on signed work, margin, delivery capacity, or collected cash. This prevents a large facility from becoming permission to spend without proof.
The UK financing environment is changing. UK Finance reports that SME gross lending rose by 9% to £68 billion in 2025, the second-highest level in 13 years, in its SME lending update. More available lending doesn't remove the execution problem. Borrowing can magnify weak pricing, poor collection, and unmanaged delivery just as quickly as it can fund productive investment.
The evidence on sustained growth is sobering. The government evidence annex reports that only 14.5% of firms achieved sustained growth between 2020 and 2023, while around two-thirds of growing businesses with ten or more employees recorded average annual employment growth of only 0% to 4%. Model the lag between sale, delivery, invoice, receipt, payroll, supplier payment, and VAT. If the plan can't survive that timing gap, reduce the investment stage or change the commercial model.
A short visual explanation can help owners and managers distinguish funding from profitable execution.
Your Implementation Roadmap and Review Cadence
A growth plan becomes useful when each priority has an owner, a measure, a deadline, and a decision rule. Don't launch every initiative at once. Use the first 90 days to establish control, prove the commercial assumptions, and create a review rhythm that survives busy periods.
The first 90 days
Days 1 to 30 should establish the baseline. Confirm the target market, service profitability, current pipeline, aged receivables, staff capacity, supplier exposure, and cash position. Clean up Xero data, agree KPI definitions, and document the assumptions behind the forecast.
Days 31 to 60 should test the engine. Run the chosen sales activity, tighten proposal and pricing controls, improve invoice timing, and remove one operational bottleneck. Assign each action to a named person. If the owner remains responsible for everything, the plan hasn't created capacity.
Days 61 to 90 should commit the next stage. Review the evidence against the forecast, decide whether to hire, outsource, automate, or pause, and update the funding requirement. Approve only the investment supported by actual pipeline quality, margin, delivery capacity, and cash conversion.
Your quarterly review should cover pipeline, pricing, margin, hiring, and cash conversion. Monthly management accounts keep the detail current, while the quarterly meeting focuses on choices rather than producing another report. Record the decision, owner, deadline, and expected financial effect.
A practical business review template and expert guide can help structure that meeting. Stewart Accounting Services is one option for businesses that want regular reports, Xero-based workflows, bookkeeping, payroll, VAT support, and planning input, with face-to-face support in Alloa, Stirling, and Falkirk or remote support across the UK.
Keep the plan commercially honest
Review the plan whenever a major assumption changes. That includes a material price change, a key employee leaving, a large customer delaying payment, a new contract with unusual delivery demands, or a funding decision. Don't wait for year-end accounts to discover that the operating model has moved away from the forecast.
Acquisitions may become relevant later, but they require more than enthusiasm and available finance. If you're considering scaling through acquisitions, first prove that your core business has reliable reporting, management capacity, clean processes, and cash discipline. Buying complexity before building control is an expensive way to postpone the work.
The objective isn't growth at any cost. It's a business that produces stronger profit, converts that profit into cash, and operates without making the owner the only person who knows how everything works.
Book a growth planning review with Stewart Accounting Services before you commit to your next hire, marketing push, or funding application. Bring your latest Xero reports, pipeline, pricing, aged receivables, and cash forecast, and use the meeting to build a practical plan with clear KPIs, funding stages, and 90-day actions for your business.
Recent Posts
12 Nov, 2026