
10 Financial KPIs Examples for UK SMEs: What to Track
Your year-end accounts land and they look respectable. Turnover of £850,000, a net profit of £96,000, and a covering letter confirming the margin is holding. Three weeks later the quarterly VAT and PAYE payment falls due and there isn't enough in the current account to cover it without leaning on the overdraft.
Nothing in the profit and loss account is wrong. The money is real. It's sitting in the sales ledger, in invoices that went out a week late and are being settled at 62 days against 30-day terms. Profit measures what you earned. Cash measures what you can spend. The gap between the two is where otherwise sound businesses come unstuck.
That gap is what a KPI pack is for. Not for the year-end file, and not for a dashboard nobody logs into, but for the decisions you make in the next four weeks: what to charge, who to chase, whether to hire, whether to borrow, whether to sell.
Below are ten financial KPI examples, each with the calculation, a worked example with real arithmetic, the decision it drives, and the action to take this month. Some of the ten will matter to you now. Two or three will matter enormously. The rest you can leave until your situation changes.
1. Gross Profit Margin
Gross profit margin shows what's left from a sale after the direct cost of delivering it. The calculation is (revenue minus cost of sales) divided by revenue, multiplied by 100. Cost of sales means materials, subcontractors, direct labour, carriage and any licence or hosting cost tied to fulfilling the job. Rent, admin wages and marketing stay out of it.
A joinery business turns over £800,000 against £520,000 of cost of sales, so gross profit is £280,000 and the margin is 35%. It raises prices 5% at the start of the new financial year and keeps every existing customer. Revenue becomes £840,000, cost of sales stays at £520,000, gross profit climbs to £320,000 and the margin is 38.1%. That extra £40,000 drops to the bottom line almost intact, because not one overhead changed to earn it.
That's a pricing decision settled with a number instead of a feeling.
Practical rule: Fix the target margin before you quote the job, not after you've won it at a price you can't deliver.
Where the calculation usually breaks
Direct labour is the commonest error. If the two people who deliver the work sit in administrative wages, the margin looks flattering and you'll price the next job too low. Split the figure by service line as well, because a blended margin hides the line quietly losing money.
- Compare month on the same month: seasonality will otherwise send you chasing phantom declines.
- Recheck after every supplier increase: a 6% materials rise absorbs a lot of a 35% margin.
- Set a floor before discounting: agree the minimum acceptable margin before a large order tempts you.
2. Net Profit Margin
Gross margin tells you the work is worth doing. Net profit margin tells you whether the business is worth running. It's net profit divided by revenue, multiplied by 100, taken after cost of sales, overheads, interest and tax.
The decision it most often settles is hiring. Say a consultancy bills £600,000 and returns £90,000 net, a 15% margin. A new administrator costs £38,000 plus employer's National Insurance and pension, so budget £44,000 all-in. Take on the hire with revenue unchanged and net profit falls to £46,000, a 7.7% margin. For that hire to stand still it has to generate £44,000 of extra gross profit, which at a 45% gross margin needs about £98,000 of additional revenue. Four minutes with a calculator answers the question better than the interview does.
Trend, not snapshot
One year's margin tells you almost nothing. Three years side by side tells you whether you're getting more efficient or quietly drifting.
- Strip out exceptional items: a one-off equipment sale or a written-off bad debt distorts the comparison.
- Do the tax planning before the year end: corporation tax sits inside net profit, so a decision taken in March beats one taken in December.
- Read it beside cash: a 12% net margin with falling cash means the profit is trapped in debtors.
3. EBITDA Margin
EBITDA margin is operating profit before interest, tax, depreciation and amortisation, divided by revenue and multiplied by 100. It strips out how the business is financed and how its assets are written down, which is why lenders and buyers reach for it first.
The decision it serves is borrowing. A facilities management company turning over £1.2m reports operating profit of £120,000 and depreciation of £30,000, so EBITDA is £150,000 and the margin 12.5%. On top of that the owner adds back £20,000 of one-off legal costs and £30,000 of director's pay above a market rate for the role. Adjusted EBITDA is £200,000 and the margin 16.7%. That adjusted figure is what the bank lends against and what a buyer will later apply a multiple to.
The adjustments are the argument
Every add-back needs a reason and a note in the file. A lender will accept one-off costs and above-market director pay. They won't accept a "one-off" that has appeared in each of the last three years.
- Write the definition on the page: EBITDA isn't a statutory measure, so record what you included and what you excluded.
- Track it against operating cash flow: EBITDA ignores working capital and capital spending, and both eat cash.
- Use it to benchmark as you scale: it's the cleanest way to see whether growth is improving operations or just enlarging them.
4. Operating Cash Flow
Operating cash flow is the cash your trading produced, after working capital moved but before financing and investment. Start with net profit, add back depreciation, subtract any increase in debtors and stock, add any increase in creditors. That's the whole calculation, and it's the number that tells you whether the business funds itself.
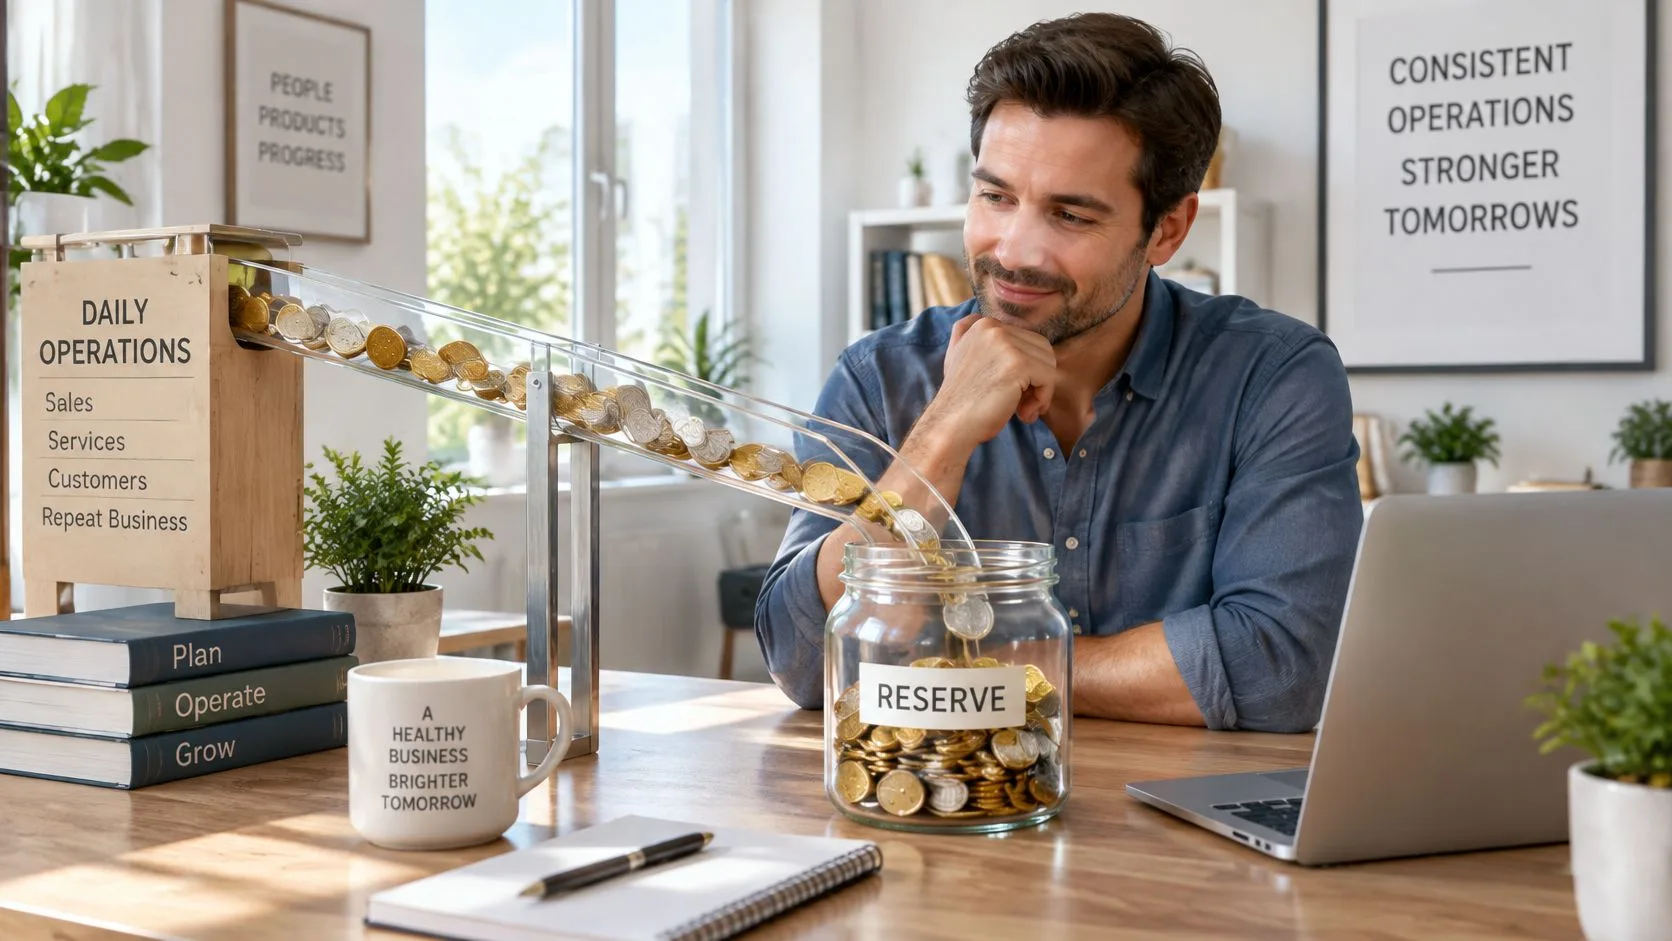
Take a business showing £150,000 of profit. Depreciation adds back £20,000, debtors rose £60,000 over the year, stock rose £15,000 and creditors rose £10,000. Operating cash flow is £105,000 (£150,000 + £20,000 − £60,000 − £15,000 + £10,000), a cash conversion of 70%. The missing £45,000 is real money sitting in your customers' bank accounts and your stockroom.
The mood on this hasn't improved. The British Business Bank's November 2024 markets spotlight, citing British Chambers of Commerce survey data, recorded only a 2% net balance of firms reporting improved cash flow in Q1 2024, rising marginally to 4% in Q2, against a pre-pandemic average of approximately 10%.
Cash doesn't care what the profit and loss account says. It cares when the invoice gets paid.
The routine that works
- Roll a 13-week forecast: it predicts the VAT quarter before the VAT quarter arrives.
- Reconcile the bank weekly: a stale bank feed turns every cash figure into a guess.
- Move tax money on receipt: transfer the VAT and PAYE element out of the current account as each invoice is paid.
A properly interlinked forecast shows how a change in debtor days lands in the same week as a payroll run, which is the point of how cash flow forecasts can help you.
5. Current Ratio
Current ratio is current assets divided by current liabilities: what you can convert to cash within twelve months, over what falls due within twelve months. Above 1 means short-term assets cover short-term debts. Below 1 means you're relying on next month's trading to pay this month's bills.
A limited company holds £320,000 of current assets (debtors £150,000, stock £90,000, cash £80,000) against £400,000 of current liabilities (trade creditors £110,000, VAT £40,000, PAYE £25,000, overdraft £90,000, director's loan £135,000). The ratio is 0.80. Two moves fix it. Refinance the £90,000 overdraft into a three-year term loan and current liabilities fall to £310,000, giving 1.03. Convert £60,000 of the director's loan to equity and they fall to £250,000, giving 1.28.
What doesn't work
Chasing debtors barely moves this ratio, and using the cash collected to pay down the overdraft actively makes it worse when the ratio is below 1, because both sides fall by the same amount. Writing off obsolete stock makes it worse again.
- Accrue VAT and PAYE properly: a ratio built on unrecorded liabilities is fiction.
- Reclassify what's long-term: a director's loan with no fixed repayment date belongs in long-term debt or equity.
- Review it monthly against the forecast: it's an early warning, not a post-mortem.
6. Debt-to-Equity Ratio
Debt-to-equity compares what the business owes with what the owners have put in and left in. Total debt divided by shareholders' equity, where equity means share capital plus retained earnings.
A company carries a £300,000 bank loan, £50,000 of hire purchase and a £100,000 director's loan, so total debt is £450,000. Equity is £300,000, made up of £100,000 share capital and £200,000 retained earnings. The ratio is 1.5. Funding the next phase with another £150,000 of borrowing takes it to 2.0. Funding the same phase by retaining £150,000 of profit instead leaves debt at £450,000 against equity of £450,000, a ratio of 1.0. Same expansion, very different risk.
Lending conditions form the backdrop. The British Business Bank's small business finance markets report puts gross bank lending to UK SMEs, excluding overdrafts, at £62.1 billion in 2024, a 4.9% nominal increase on 2023 and the third-highest level since records began in 2012, though well below the £104.9 billion lent in 2020 under the government-backed pandemic schemes.
Before you draw down: compare the all-in interest rate with the return the money will earn. Borrowing at 9% to fund work that returns 6% makes the business smaller, not bigger.
If the mechanics of gearing are still hazy, this walkthrough is worth eight minutes.
- Define debt consistently: include directors' loans, hire purchase and invoice finance.
- Test the covenant before you sign: debt-service cover and interest cover are what the lender monitors.
- Review it before any major purchase: and again in the two years before a sale.
7. Days Sales Outstanding
Days sales outstanding is how long your customers take to pay, on average. Trade debtors divided by credit sales, multiplied by the days in the period.
A services business carries £180,000 of debtors against £1,200,000 of annual credit sales. DSO is (£180,000 ÷ £1,200,000) × 365, which is 55 days. Set a 35-day target and debtors at the same sales level would be about £115,000, releasing roughly £65,000 of cash without a single extra sale. That's the decision: deposits, automated reminders, or a credit check on the two slowest accounts.
This isn't a niche problem. Government-commissioned research published by the Small Business Commissioner estimates UK businesses are owed around £26 billion in overdue payments at any given time, with more than 1.5 million UK businesses, around 28% of all businesses, affected each year.
Set the trigger, not just the target
A target is a wish. A trigger is a rule that fires. I'd set the trigger at your agreed terms plus ten days, and name the person who owns the call to that customer.
- Segment by customer: three large clients on 60-day terms can make a healthy ledger look sick.
- Invoice the day you deliver: every day between delivery and invoice is free credit you granted.
- Take a deposit from new clients: 30% up front filters out the ones who were never going to pay on time anyway.
- Work the aged debtors report weekly: start with the oldest invoice, not the largest.
For the other side of the equation, shortening your cash conversion cycle to free up your cash covers stock and creditor days alongside it.
8. Return on Capital Employed
ROCE is operating profit divided by capital employed, multiplied by 100, where capital employed is total assets minus current liabilities. It answers a question margin can't: is the money tied up in this business earning more than it would elsewhere?
A manufacturer holds total assets of £900,000 and current liabilities of £300,000, so capital employed is £600,000. Operating profit is £120,000, a ROCE of 20%. It considers a £150,000 machine funded by a loan at 8%, expected to add £24,000 of operating profit a year. Capital employed rises to £750,000 and operating profit to £144,000, so ROCE falls to 19.2%. The investment is still right, because 19.2% comfortably beats the 8% cost of the money.
When a lower ROCE is the right answer
Growth usually dilutes ROCE before it improves it. The test isn't whether the percentage fell, it's whether the return still clears the cost of capital.
Profitability alone won't tell you that. In the trading year covered by the British Business Bank's small business finance report, 74% of SMEs were profitable and 9% made a loss, which is a reminder that a profit and loss account doesn't show what the capital cost to earn.
- Compare ROCE with your borrowing rate: a return below the rate destroys value, however good the sales pitch sounded.
- Keep valuations consistent: revaluing property mid-comparison flatters the number year on year.
- Use it for buy-or-outsource calls: it settles machinery, vehicle and premises decisions faster than instinct does.
9. Revenue Growth Rate
Revenue growth rate is the change in sales between two periods, divided by the earlier period, multiplied by 100. It's the easiest KPI to calculate and the easiest to misread, because growth on its own says nothing about whether it was worth having.
A business moves from £720,000 to £900,000, growth of 25%. Gross margin slipped from 38% to 34% over the same period, so gross profit went from £273,600 to £306,000, an increase of 11.8%. Headcount went from 12 to 14, so revenue per head rose from £60,000 to £64,285, about 7%. That's a real gain, but it's under a third of the headline.
Measure the growth, then measure what it cost
Headline growth is a vanity number until you know what it consumed.
- Use rolling twelve months: month-on-month comparisons on a seasonal business produce noise, not insight.
- Split by customer and product line: growth concentrated in one account is concentration risk, not success.
- Watch revenue per head: it's the number that tells you whether the last hire paid for itself.
Technology is where most owners expect that gain to arrive. The SME Digital Adoption Taskforce final report puts firm-level productivity improvements at 7% to 18% per technology adopted, and projects that a 1% productivity improvement across UK SMEs over five years could add £94 billion a year to GDP. The word to hold onto is "could". The gain shows up in bookkeeping hours per client, invoice-processing time and debtor days, not in how many people log into the dashboard.
Growth that arrives with more people and a thinner margin is the pattern to look for.
Watch for this: revenue rising while revenue per head falls means you're buying turnover with extra people, and the margin will send you the bill.
10. Break-Even Point
Break-even is the sales level at which revenue equals total costs and profit is zero. Divide fixed costs by the contribution margin ratio, where the ratio is (selling price minus variable cost) divided by selling price. Fixed costs are the ones you pay whether you trade or not: rent, salaried staff, insurance, software subscriptions. Variable costs move with sales: materials, subcontractors, card fees.
Say fixed costs are £180,000 a year and variable costs run at 40% of revenue, so the contribution margin is 60%. Break-even revenue is £180,000 ÷ 0.60, which is £300,000, or £25,000 a month. Two levers change it. Cutting £18,000 of fixed cost by moving to a smaller unit drops break-even to £270,000. Raising prices 5% while variable costs stay put lifts the contribution margin to 61.9% and drops break-even to £290,800.
What it changes on a Monday morning
Break-even turns an annual ambition into a weekly target the whole team can hold.
- Recalculate quarterly: energy, insurance and wages move, and a stale break-even is worse than none.
- Model the price change before you announce it: it shows how much volume you can lose and still be better off.
- Set the minimum monthly sales target from it: £25,000 a month is a number a sales team can own.
How the ten financial KPIs compare on formula, purpose and main limitation
| KPI | Core Formula | What It Shows | Main Limitation |
|---|---|---|---|
| Gross Profit Margin | (Revenue − Cost of Sales) / Revenue × 100 | Share of revenue left after direct costs; indicates pricing and cost control | Excludes overheads and depends on consistent cost classification |
| Net Profit Margin | Net Profit / Revenue × 100 | Share of revenue retained as profit after all costs, interest, and tax | Can be distorted by one-off items, accounting policies, and tax decisions |
| EBITDA Margin | EBITDA / Revenue × 100 | Operating profitability before interest, tax, depreciation, and amortisation | Excludes capital costs and may overstate cash available |
| Operating Cash Flow | Cash from operating activities, adjusted for non-cash items and working capital changes | Cash generated by core trading to meet day-to-day obligations | Can fluctuate by period and requires accurate, timely bookkeeping |
| Current Ratio | Current Assets / Current Liabilities | Ability to cover short-term obligations with short-term assets | Does not reflect payment timing; stock values and sector differences can mislead |
| Debt-to-Equity Ratio | Total Debt / Shareholders' Equity | Reliance on borrowing relative to owner funding and retained profits | Definitions of debt vary, and book equity may not reflect market value |
| Days Sales Outstanding (DSO) | (Trade Debtors / Credit Sales) × Days in Period | Average time taken to collect payment after a credit sale | Averages can hide overdue accounts and be distorted by large invoices or seasonality |
| Return on Capital Employed (ROCE) | EBIT / (Total Assets − Current Liabilities) × 100 | How efficiently the business generates operating profit from capital employed | Asset values and depreciation methods affect results; less useful for asset-light businesses |
| Revenue Growth Rate | (Current Revenue − Prior Revenue) / Prior Revenue × 100 | Change in sales over a chosen period and business growth momentum | Does not measure profitability or cash generation; seasonality can distort comparisons |
| Break-Even Point | Fixed Costs / Contribution Margin Ratio | Sales level at which revenue equals total costs | Assumes stable prices and costs and requires accurate cost classification |
Turn These Numbers Into a Monthly Money Routine
Ten metrics is a reading list, not a system. Tracking all of them every month produces a report nobody acts on. Pick three that match the problem in front of you this quarter.
- If cash is the constraint: operating cash flow, days sales outstanding and the current ratio.
- If margin is the problem: gross profit margin by service line, net profit margin and break-even.
- If the question is whether to grow: revenue growth rate, revenue per head and ROCE.
Put those three on one page with a target, last month's actual and a one-line comment. One page reviewed on the same date each month beats a twenty-tab dashboard opened once. Take a business with revenue of £900,000, a 34% gross margin and DSO of 55 days. It has roughly £135,000 tied up in debtors. Pull DSO to 40 days and about £37,000 of cash arrives without a new customer, a new product or a single extra hour of selling. That's the sort of connection the monthly meeting should be making.
Value comes from linking the numbers rather than reading them in isolation. A forecast built month by month across cash flow, profit and loss and balance sheet shows the knock-on effect of a decision before you commit to it. Stewart Accounting Services, a Chartered Accountants firm based in Alloa with offices in Stirling and Falkirk, builds fully interlinked projections for exactly that reason, so a change in debtor days or a new hire shows its effect on cash, profit and the balance sheet at the same time. The firm also handles VAT returns, payroll and year-end accounts for limited companies, which is where a lot of the cash pressure on this page originates in the first place.
Set your three targets this week. Put the review in the diary. Bring the rolling cash forecast to it, not just the profit and loss account, and the numbers stop being a scorecard and start being a steering wheel.
If your management accounts arrive too late to change any decision, or you'd like a KPI pack built around the three numbers that move your business, talk to Stewart Accounting Services. A first conversation will establish which metrics fit where you are now and what a monthly routine would look like for a business your size.
Recent Posts
12 Nov, 2026
12 Nov, 2026