
Seafarers Earnings Deductions: UK Rules and How to Claim
You're a second engineer, home after a long rotation. Your wages have arrived, the payslip shows tax deducted, and a crewmate says you should be able to claim it all back. You've spent months away, but your flights, leave and pay dates don't line up neatly.
That's where seafarers earnings deductions become confusing. The useful starting question isn't “Was I offshore when I got paid?” It's “Which period does this pay belong to, and does that period qualify?”
What the Seafarers Earnings Deduction Actually Does
The Seafarers' Earnings Deduction (SED) reduces taxable employment income by the earnings attributable to an eligible period. It doesn't make you exempt from tax as a person, and it doesn't automatically cover every payment from a maritime employer.
Think of your employment pay as a jug being poured along a calendar. The qualifying portion is lifted out of your taxable employment income; the rest remains subject to the normal rules. The important detail is where each portion belongs on that calendar, not when the employer transfers it into your bank account.
Your payslip is the starting evidence, not the final answer.
A deduction, not a blanket exemption
Qualifying earnings can be removed from the income tax calculation without making unrelated income tax-free. Nor should you assume that an income tax deduction settles separate payroll questions, such as National Insurance.
Where an employer operates PAYE without an adjustment for SED, tax may already have been deducted from qualifying wages. A Self Assessment claim can then establish the correct income tax position and any repayment due.
Practical rule: Establish the eligible dates before deciding how much pay to claim. A convincing payslip total can still produce the wrong deduction.
A sound claim therefore needs both a qualifying employment history and a dated earnings calculation. You should be able to explain the duties, demonstrate the absence pattern, identify the relevant earnings and trace the return figure back to your records.
Who Qualifies for the Seafarers Earnings Deduction
The four eligibility tests and the evidence for each
| Requirement | What HMRC expects | Evidence to keep |
|---|---|---|
| Duties on a ship | All duties on a ship, or most duties on a ship with only incidental other duties | Employment contract, vessel names, voyage schedules |
| Duties outside the UK | Duties performed wholly or partly outside the UK | Voyage itineraries, port call records, joining and sign-off dates |
| Eligible period | A sufficiently long period made up mainly of days outside the UK | Day-by-day travel log with midnight locations |
| Tax year link | Eligible period falls wholly or partly within the tax year claimed, with relevant earnings attributable to it | Pay records showing the periods earnings cover |
| UK residence | Generally UK tax residence, or residence in a qualifying EEA state under the extension | Residence history and tax residence status records |
| Non-UK-resident EEA seafarer | Deduction limited to earnings from seafaring duties performed in UK waters | Record of UK-waters duties and associated earnings |
The table separates the eligible-period and tax-year checks, and shows the restriction affecting non-UK-resident EEA claims. These details sit within the broader tests concerning duties, overseas work, timing and residence.
Check duties before counting days
Start with what your employment really requires. An officer who completes occasional shore-based administration connected with shipboard work may satisfy the duties condition. Someone mainly employed in a shore office doesn't qualify just because they sometimes travel aboard.
Keep the job description alongside the contract. If your role changes, record when it changed and what you did afterwards, rather than relying on a job title that stayed the same.
Next, establish that duties were performed wholly or partly outside the UK. Vessel itineraries help, but they need to connect to your own service dates: a ship's international route doesn't prove you were aboard during its overseas passage.
Check timing and residence separately
The eligible period must connect with the tax year being claimed. Employment continuing throughout a tax year doesn't establish that every payment belongs to an eligible period.
Residence is a separate question from travel. HMRC's Employment Income Manual records an extension from 6 April 2011 for residents of another European Economic Area state, subject to the other conditions, and restricts non-UK-resident EEA seafarers' deductions to earnings from seafaring duties performed in UK waters.
Don't infer tax residence from nationality, a home address or the flag of the vessel. Establish the relevant status from your circumstances and retain the supporting records.
If a requirement fails, don't carry the affected earnings into the calculation merely because the absence record looks strong.
How the 365-Day Eligible Period Is Counted
Your day count follows your location at midnight, not your timesheet. A non-working day abroad can count as an absence; a day spent working aboard in a UK port won't count if you remain in the UK at midnight.
Under section 378 of the Income Tax (Earnings and Pensions) Act 2003, as explained in HMRC's eligible-period guidance, the central requirement is an eligible period of at least 365 days, made up mainly of days outside the UK; its example combines 330 days working abroad, 30 days back in the UK and a further 7 days abroad.
That example matters because an eligible period isn't necessarily uninterrupted overseas employment. Permitted UK visits can sit within the calendar calculation.
Day-count rules that decide whether a period qualifies
HMRC's HS205 helpsheet explains that no single return visit may exceed 183 consecutive days, total UK days must not exceed half of the relevant period, and the period can begin or end on any date.
| Rule | Test applied | Practical effect |
|---|---|---|
| Day of absence | Outside the UK at midnight | Counts without work being performed; a UK port day ending in the UK doesn't count |
| Single UK visit | Each return visit stays within the permitted consecutive-day limit | A long UK stay can break the proposed period |
| Total UK time | UK days stay within the permitted share of the whole period | Frequent short visits can still prevent qualification |
| Period boundaries | Period can start or end on any date | An eligible period can cross a tax-year boundary |
| Leave pay | Qualifying leave pay is attributed to the eligible period ending on return | Terminal leave pay may belong to the earlier eligible period |
Build a calendar, not an estimate
Use Excel or Google Sheets with a row for each date. Add columns for midnight location, UK or abroad status, vessel, employment, travel event and supporting document.
Record arrival and departure timings rather than marking every flight day as overseas. If a journey crosses midnight, check the itinerary against the location you've entered.
Keep UK leave visible, including gaps between contracts. Don't remove inconvenient days from the spreadsheet or restart the calculation without checking the effect on the proposed period.
A discharge book can demonstrate service aboard. It doesn't necessarily establish where you spent every midnight between voyages.
Start the log from the first relevant joining journey and preserve the evidence alongside it. Mark uncertain dates for checking rather than turning an assumption into a claimed absence.
How to Calculate Your Deduction Step by Step
The calculation is mainly an allocation exercise, not a percentage exercise. HMRC's HS205 Self Assessment helpsheet describes SED as generally a 100% deduction from qualifying employment earnings, with only earnings arising in the eligible period qualifying.
Set out the payroll and calendar together before entering a claim.
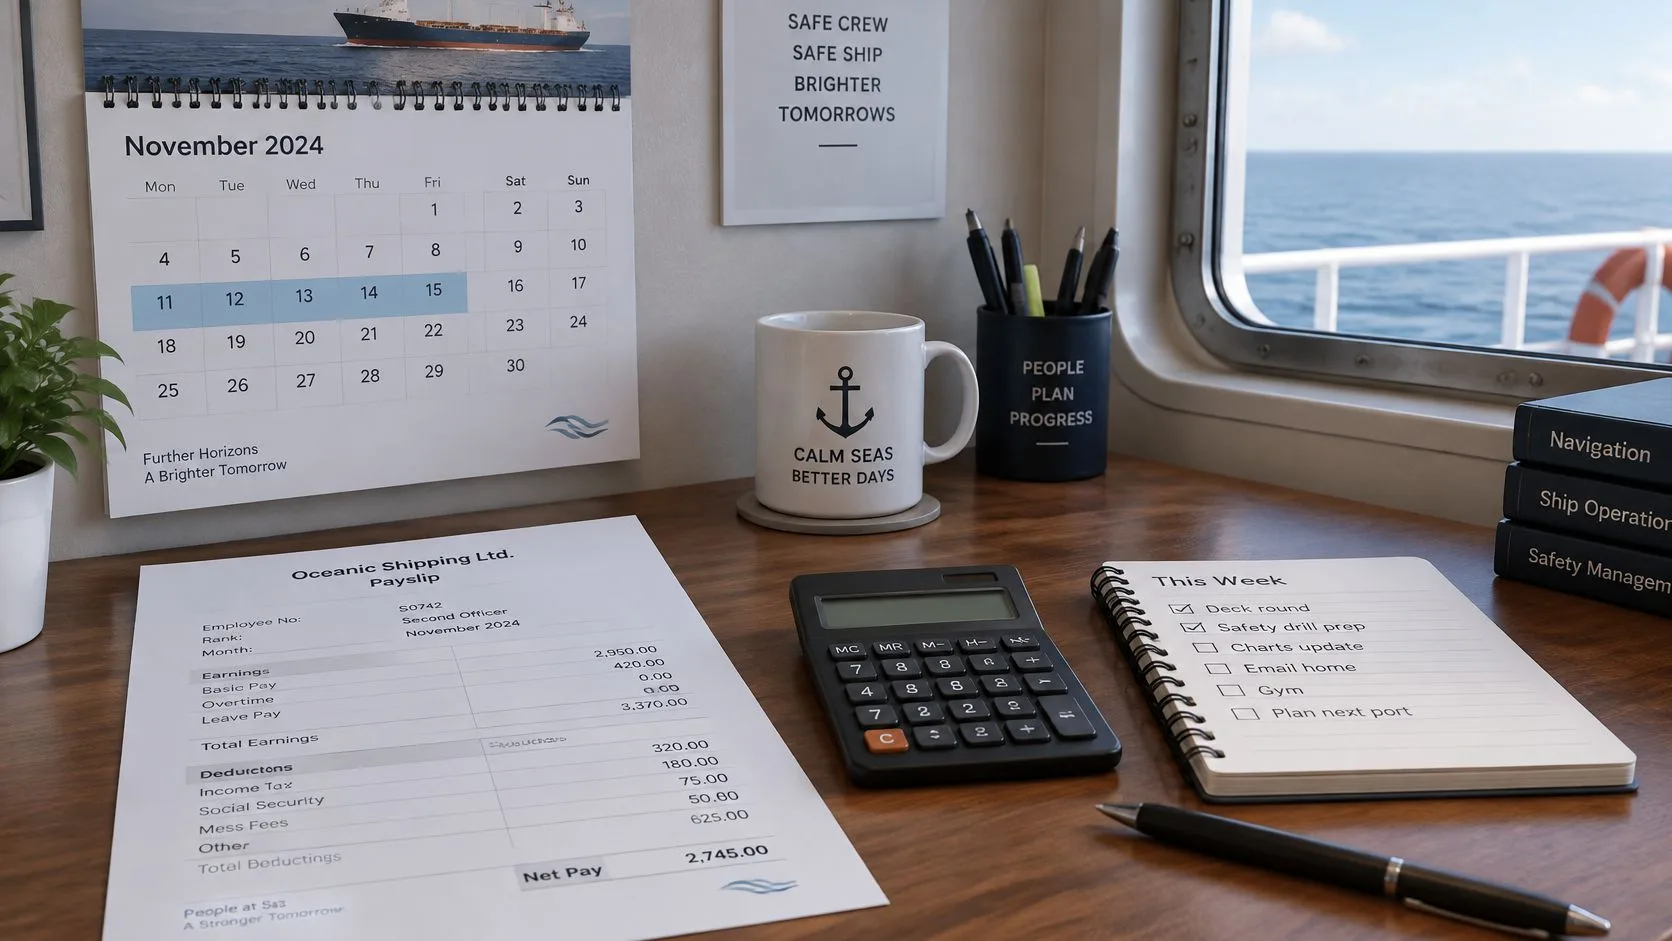
Build the supporting schedule
Gather the employment evidence. Collect contracts, payslips, voyage schedules and vessel records. Include contract amendments so you can identify changes in duties or pay.
Put movements on a single sheet. List joining, sign-on, sign-off, UK arrival and overseas departure events in date order. Separate leaving the vessel from arriving home, because they may happen on different days.
Classify the calendar. Mark each day using the midnight-location rule. Attach a document reference to travel days that could otherwise be disputed.
Test the proposed eligible period. Check its duration, individual UK visits and overall UK presence. Save the calculation rather than retaining only a final pass-or-fail note.
Allocate each pay line. Identify the service or entitlement period covered by salary, overtime, bonuses and leave pay. Ask payroll for an explanation where a payslip gives only a payment date.
Separate the tax-year shares. Keep the eligible-period calculation intact while identifying earnings relevant to each return. The absence calendar and the annual tax reporting schedule serve different purposes.
Reconcile to gross payroll. Account for the full employment total shown by payslips and the P60, separating qualifying earnings from amounts outside the claim. Don't use the net amount received after deductions.
Save a dated version. Retain the spreadsheet, source documents and explanations for adjustments. A reviewer should be able to reproduce your result without guessing what a colour or abbreviation means.
Apply the method to irregular pay
Suppose your salary continues through a long overseas rotation, but the rotation starts part-way through a payroll month and finishes in a later tax year. Don't treat the whole opening payslip as qualifying just because most of it relates to the voyage.
Identify the dates covered by that salary line and use the contractual pay basis to support any split. Then distinguish service pay from leave pay, reimbursements and later adjustments rather than applying a daily fraction to everything.
Use the video alongside your documents, not as a substitute for the dated calculation.
The jug analogy helps here: you're identifying the qualifying contents, not lifting the entire year's jug out of taxable income. Applying SED to annual gross pay without that allocation can overstate the deduction.
Claiming Through PAYE and Self Assessment
PAYE records what your employer has deducted as wages are paid. Self Assessment establishes the final annual position, including the SED claim and any resulting overpayment.
If tax has been deducted from qualifying pay, the repayment isn't automatically the deduction itself. The deduction reduces taxable earnings; the tax calculation then determines the effect after accounting for the rest of your return.
Which claim route fits each situation
| Situation | Route | What to check |
|---|---|---|
| Single employer, full claim in one tax year | Self Assessment return, employment pages | Qualifying amount matches the eligible-period schedule |
| Several employers in one tax year | Self Assessment with employer-specific employment entries and schedules | Earnings separated by employer and eligible period |
| Eligible period spans tax years | Claim the relevant earnings in each year's return | Consistent day count and no duplicated earnings |
| Employer has already adjusted payroll | Confirm the treatment before filing | Payroll treatment and return entries don't duplicate relief |
| Tax deducted under PAYE on qualifying pay | Self Assessment claim reflecting the deduction | Tax deducted agrees with payroll records and the claim agrees with the schedule |
Keep gross earnings and the deduction identifiable
Don't replace the P60 earnings figure with a reduced figure and assume the claim is complete. Follow the relevant return or software instructions: record employment income and tax deducted accurately, and enter the SED claim in the appropriate deduction field.
The resulting taxable earnings should reflect the qualifying deduction, but the underlying gross pay must remain traceable. Keep the calculation available even where the filing process doesn't ask you to upload it.
Use the HS205 helpsheet applicable to the return you're completing. For the wider filing process, this step-by-step UK guide to filing a Self Assessment return explains how to organise the return.
Agree the employer's part
Ask payroll for the P60, dated pay breakdowns and explanations of any retrospective adjustments. Where the employer has changed the PAYE treatment, establish exactly what was adjusted rather than assuming it has already settled your personal claim.
The employer supplies and corrects payroll information; you remain responsible for the accuracy of your return. Agree who will resolve missing records and who will prepare the supporting calculation.
Before submitting, trace the claimed deduction from the return back to employer totals and then to individual pay lines. Any unexplained difference needs resolving, not rounding away.
Worked Examples From Rotations to Full Claims
Suppose Tom is a chief engineer joining a Gulf rotation late in the year and returning during a later winter. His employer pays salary regularly, leave after he comes home and a performance bonus later still.
Tom shouldn't classify those payments by looking at the bank statement alone. He needs his service dates, the completed absence calculation and the terms under which each payment was earned.
Worked scenarios and their outcomes
These scenarios illustrate the method, rather than establish entitlement for every similar rotation.
| Scenario | Key dates or facts | Outcome | Why it falls that way |
|---|---|---|---|
| Terminal leave after Gulf rotation | Overseas service followed by qualifying terminal leave | Leave pay can remain attributable to the preceding eligible period | The entitlement relates to that preceding service |
| Period straddling a tax-year boundary | The eligible period continues across the annual reporting boundary | Relevant earnings appear in the appropriate annual returns | The eligible-period calculation doesn't replace annual reporting |
| Long UK stay | A continuous return visit exceeds the permitted limit | Relief isn't available on that proposed calculation | The visit breaks the eligible-period test |
| Bonus paid after the period | A later payment rewards work during the overseas service period | Examine attribution to the earlier eligible period | The payment's purpose and terms matter, not merely its banking date |
Why Tom's leave needs its own check
Tom's leave starts after he gets home, but that doesn't automatically make the associated pay non-qualifying. If it is qualifying leave pay attributable to the completed eligible period, the schedule should record that connection.
He keeps the leave entitlement calculation and employer confirmation with the payslip. He doesn't mark every post-return payment as excluded, or include ordinary pay from a new shore role because it arrived alongside leave pay.
Reporting boundaries and a broken period
Where Tom's eligible period crosses a tax-year boundary, he maintains a continuous travel record but prepares the relevant annual earnings totals separately. He doesn't claim the entire rotation in the year he signs off.
A long UK stay produces a different problem. Before allocating pay, Tom must establish whether the proposed period still qualifies; if it doesn't, he needs to test whether another valid period exists rather than force the original dates to fit.
A bonus needs evidence of attribution
For a later bonus, Tom asks what performance period and duties the award covers. A written bonus statement is more useful than an assumption based on the month it reached his account.
He also checks the correct tax-year treatment. Attribution to an eligible period and the tax year in which earnings are reportable are related but distinct questions. A later payment shouldn't automatically be moved into an earlier return without checking the earnings rules.
Common Pitfalls for Employers and Seafarers
Treating an entire tax year as qualifying is an avoidable starting error. Employment can continue while duties, travel patterns and eligible-period boundaries change.
The fix is to make each assumption visible. Your schedule should show why an amount qualifies, not merely display the amount you hope to deduct.
Employer pitfalls
- Using payday as the service date. Supply the period covered by each pay line, including retrospective salary and overtime.
- Missing joining and sign-off records. Keep dated crew movements with contract records so payroll can explain the employment timeline.
- Carrying assumptions across contract changes. Review changed duties, vessels and terms before treating subsequent earnings in the same way.
- Misclassifying leave pay. Identify the service that generated the leave entitlement and record that connection.
- Providing incomplete annual figures. Issue accurate payroll records and resolve discrepancies before the seafarer files.
Seafarer pitfalls
- Counting shifts instead of absences. Use midnight locations supported by travel and vessel evidence.
- Ignoring a lengthy return home. Retest the proposed period before carrying on with the pay calculation.
- Omitting another employer. Reconcile every employment separately, then check the combined return.
- Assuming residence is obvious. Keep a residence history and obtain advice where the position is uncertain.
- Putting a cross-year claim into a single return. Separate annual reporting without losing the continuous eligible-period evidence.
- Treating a tax code as proof of entitlement. Check the underlying claim independently; this guide to understanding your tax code explains what the code does.
Before submission: Replace every unexplained spreadsheet adjustment with a document reference or a written calculation.
An amount can look reasonable and still be unsupported. If a reviewer can't tell whether a figure represents salary, leave, a bonus or an estimate, the working needs more detail.
Confirm Your Records Before You Claim
A straightforward employment history with a complete travel log and reconciled payroll may be manageable through Self Assessment using the relevant HS205 instructions. Complexity, rather than the size of a potential repayment alone, should guide whether you seek help.
Your pre-filing checklist
- Dated absence log. Each relevant date has a midnight location, with evidence for travel and uncertain movements.
- Reconciled earnings schedule. Qualifying and non-qualifying amounts account for the gross employment figures.
- Residence evidence. Your claimed status is supported by your actual circumstances.
- Documented allocations. Leave, bonuses and payroll corrections have an explanation beyond their payment dates.
- Matching return entries. Employment income, tax deducted and the SED figure agree with the supporting records.
Keep these documents together rather than spread across email accounts and crew-management apps. This guide to records to keep for Self Assessment can help you organise the wider filing evidence.
When a review is sensible
Seek a review if you have several employers, a period crossing tax years, prolonged or irregular UK presence, uncertain residence, or payroll adjustments you can't reconcile. These situations require more than checking whether a final total looks plausible.
Missing evidence is also a reason to pause. Ask the employer for the pay breakdown or retrieve the travel record before submitting an unsupported claim.
Stewart Accounting Services supports individuals with Self Assessment and employers with payroll, so you can request an optional review of the schedule before filing. Assemble the records, test eligibility and reconcile the earnings first. Then either submit a claim you can explain or ask for help with the specific dates and amounts you can't resolve.
Recent Posts
25 Oct, 2026