
VAT Due Date Rules for UK Businesses: A Complete 2026 Guide
You've finished the quarter, your bookkeeping is nearly reconciled, and then the question arrives: when is the VAT due date? The answer sounds simple, but the correct date depends on your VAT accounting period, filing method and scheme. A return submitted on time can still create a problem if the payment reaches HMRC late.
For most UK businesses filing quarterly online, the practical rule is one calendar month and seven days after the end of the VAT accounting period. HMRC's guidance confirms that this is normally both the filing deadline and the payment deadline for standard online returns. You can check the wider obligations that follow registration in this guide to VAT responsibilities.
Where Your VAT Due Date Actually Falls in the Calendar
Start with the period shown on your VAT return, rather than the date you issued your final invoice. Suppose your VAT 100 return covers 1 January 2026 to 31 March 2026. The accounting period ends on 31 March 2026, and that quarter-end determines the deadline.
For a standard online return, HMRC normally expects the VAT return and payment by 7 May 2026. That date is calculated by adding one calendar month to the quarter-end, reaching 30 April, then adding seven calendar days. HMRC describes the standard deadline in its VAT return submission guidance.
Count calendar days, not working days
The date is set by HMRC. You don't choose a more convenient day, and a bank holiday doesn't automatically move the obligation. In 2026, the early April Easter bank holiday period falls close to the end of this quarter, so leaving the return until the final evening creates avoidable risk.
Many owners put an internal deadline roughly seven working days before the official date. That isn't an HMRC extension. It's a sensible buffer for correcting errors, resolving missing invoices and allowing a bank payment to settle.
Practical rule: Treat the HMRC deadline as the latest safe date for a completed return and cleared payment, not as the date to begin checking your figures.
Check your scheme before relying on the date
The example applies to standard online quarterly filing. Payments on Account and Annual Accounting use different payment arrangements, so a business can't safely copy the quarterly date into every calendar.
The key point is straightforward. Find your period end, identify your scheme, then calculate the correct filing and payment date. For most quarterly online filers, that means the one-month-and-seven-day rule.
The Standard One Month and Seven Day Rule Explained
The phrase one month and seven days contains two separate parts. The first part takes you from the end of the VAT accounting period to the end of the following calendar month. The second adds seven calendar days for online returns, which is why HMRC's practical deadline is commonly expressed in this way.
Using the March example, the calculation is:
- Period end: 31 March 2026.
- One calendar month: 30 April 2026.
- Seven calendar days: 7 May 2026.
- Final online deadline: 7 May 2026.
HMRC's officer guidance links the standard deadline to regulation 25(1) of the VAT Regulations 1995. The online timetable is therefore not an informal grace period created by accounting software. It forms part of the filing framework described in HMRC's VAT Notice 700/12 guidance.
Filing and payment must both arrive on time
For a standard online filer, the VAT 100 must reach HMRC by 7 May. Your payment must also have cleared HMRC's bank account by that date. Submitting the return on 7 May doesn't give you another period in which to pay.
This distinction causes many avoidable errors. A business owner may press “submit”, see a confirmation screen and assume the obligation is complete, while the payment instruction remains pending or is rejected by the bank. The return and the money are separate actions, even though they normally share the same deadline.
What happens around weekends
HMRC's practical instructions require businesses to plan for bank processing and non-working days. If a payment date falls at an awkward time, don't assume that sending it on the date is enough. Check when the funds will reach HMRC, particularly if you're using BACS or another method that doesn't settle immediately.
The seven days are available because the return is filed electronically, but they aren't a general payment cushion. Paper returns follow the due date shown on the return, while special schemes have their own timetable. Your accounting software can calculate the date, but it can't remove the need to check the payment method.
Comparing Quarterly Monthly Annual and Cash Accounting Deadlines
Different VAT schemes change how often you report and how you manage cash. They don't all create the same calendar, so identify your scheme before setting recurring reminders.
| VAT Scheme deadline comparison for 2026 | Return Frequency | Deadline Rule | Payment Timing |
|---|---|---|---|
| Standard quarterly | Quarterly | One calendar month and seven days after the period end for online filing | Payment must clear by the same deadline |
| Monthly filing | Monthly | One calendar month and seven days after each monthly period end for online filing | Payment must clear by the return deadline |
| Annual Accounting | Annual return | Normally two calendar months after the VAT period ends | Payments on account follow the scheme timetable, with a final balancing payment |
| Cash Accounting | Usually quarterly | The standard quarterly online deadline normally applies | VAT is calculated using qualifying cash received and paid |
Quarterly and monthly filing
A standard quarterly filer generally works towards four return deadlines each year. A monthly filer has a much tighter routine, with each monthly period followed by the same one-month-and-seven-day calculation.
Monthly filing can suit businesses that regularly reclaim VAT, but it demands disciplined bookkeeping. You can't allow purchase invoices, credit notes or bank reconciliations to accumulate until year-end. The return cycle arrives quickly, and missing one month can disrupt the next calculation.
Annual Accounting
Annual Accounting changes both reporting frequency and cash management. HMRC says the annual return is normally due two calendar months after the end of the VAT period. If the accounting period is less than four months, the return is due one month after the end instead.
The scheme can also require payments during the year. The payment profile, rather than the standard quarterly deadline, controls those instalments. Businesses considering wider tax planning may find this small business taxation 2026 guide useful for comparing their obligations more broadly.
Cash Accounting
Cash Accounting changes when you account for VAT, not necessarily when the return is due. You generally calculate VAT by reference to payments received and made under the scheme rules, while the return still follows the relevant filing cycle.
That distinction matters for a business with slow-paying customers. The scheme can align VAT reporting more closely with cash movement, but it doesn't remove the need for accurate records or a reliable deadline process. See this explanation of VAT Cash Accounting before deciding whether the scheme fits your invoicing pattern.
A Practical VAT Calendar for 2026 With Worked Examples
A quarter ending on 30 June does not create a July payment deadline. For a standard quarterly online filer, HMRC normally allows one calendar month plus seven days after the period ends. The safest way to use the calendar is to match each quarter-end with its projected filing and payment date, then confirm the deadline shown in your HMRC account.
| Quarter End / Period | Standard Online Deadline | Annual Accounting Interim Due | Payments on Account Due |
|---|---|---|---|
| 31 March 2026, January to March | 7 May 2026, projected deadline for period ending 31 March 2026 | Depends on annual period start | Relevant last working day under the scheme |
| 30 June 2026, April to June | 7 August 2026, projected deadline for period ending 30 June 2026 | Depends on annual period start | Relevant last working day under the scheme |
| 30 September 2026, July to September | 7 November 2026, projected deadline for period ending 30 September 2026 | Depends on annual period start | Relevant last working day under the scheme |
| 31 December 2026, October to December | 7 February 2027, projected deadline for period ending 31 December 2026 | Depends on annual period start | Relevant last working day under the scheme |
Dates are based on the one-month-and-seven-day rule. Confirm the exact deadline in your HMRC account, particularly where weekends, bank holidays or scheme-specific arrangements affect payment processing.
Two quarterly examples
For a quarter ending 31 March 2026, count one calendar month to 30 April, then seven calendar days to 7 May 2026. The VAT return and cleared payment should reach HMRC by that projected date.
For a quarter ending 30 June 2026, one calendar month takes you to 31 July. Seven more days gives 7 August 2026. This simple two-part calculation works like marking the end of the trading quarter first, then adding the reporting window.
The final quarter needs extra care. A period ending 31 December 2026 has a projected online deadline of 7 February 2027. Although the sales and purchases belong to 2026, the return and payment belong on the 2027 compliance calendar.
Special payment calendars
Annual Accounting uses a separate payment pattern. Instalments depend on the start and length of the annual VAT period, with the final balancing payment due within one month for periods under four months, or within two months for periods lasting from four to eleven months. The annual return date and instalment dates should therefore be recorded separately.
Payments on Account follow another timetable. Instalments are due on the last working day of months two and three of each quarter, and the seven-day electronic extension does not apply. Mark these dates independently from the standard VAT return deadline.
A payment sent on the 8th when the due date was the 7th is late. Bank holidays, weekends and banking cut-off times can affect when HMRC receives cleared funds, so check the account and contact HMRC promptly rather than assuming the payment will be treated as on time.
What Really Happens When You Miss the VAT Due Date
Late VAT compliance has two separate parts: late filing and late payment. Submitting the VAT 100 late can create a filing penalty, while paying the VAT late can create interest and late-payment consequences. Filing on time doesn't protect you if the money reaches HMRC after the payment deadline.
HMRC's current penalty approach includes a points-based system for late returns. The amount owed doesn't determine whether a filing obligation exists, so a nil or repayment return still needs to arrive by its deadline. Late payment is assessed separately, with interest applying to overdue VAT from the relevant point under HMRC's rules.
Why the trend matters to SMEs
Independent reporting in 2026 cited HMRC data showing nearly 582,000 fines for late VAT payments in the prior year, compared with 569,000 previously, while penalties totalled about £302 million, compared with £294 million. Those figures are reported by Accountancy Age's coverage of VAT investigations and enforcement.
The lesson isn't that every late payment will produce the same result. It is that enforcement is a growing practical burden, particularly for businesses whose funds clear late or whose owners confuse filing with payment. A deadline reminder must cover both actions.
Filing early doesn't settle the VAT bill. Check the bank settlement, not just the submission receipt.
When cash is tight
If you know you can't pay in full, contact HMRC before the deadline and discuss a Time to Pay arrangement. You can also review practical funding considerations in this resource on leveraging loans for tax optimisation, but borrowing shouldn't replace a proper cashflow forecast.
A business that repeatedly pays late may face further compliance attention and may find it harder to demonstrate reliable tax management when seeking arrangements with HMRC or applying for external credit. Use the VAT payment plan service information when you need help preparing for a payment discussion.
The right response to a missed date is quick action. Submit any outstanding return, confirm the precise amount due, make the payment using a method that settles promptly and keep records of every confirmation.
Building Reminders and Cashflow Habits Around Your Deadline
A reliable VAT process starts before the quarter closes. Set an internal bookkeeping cut-off about two weeks before the HMRC deadline, giving your team time to reconcile sales, purchases, bank transactions and outstanding queries.
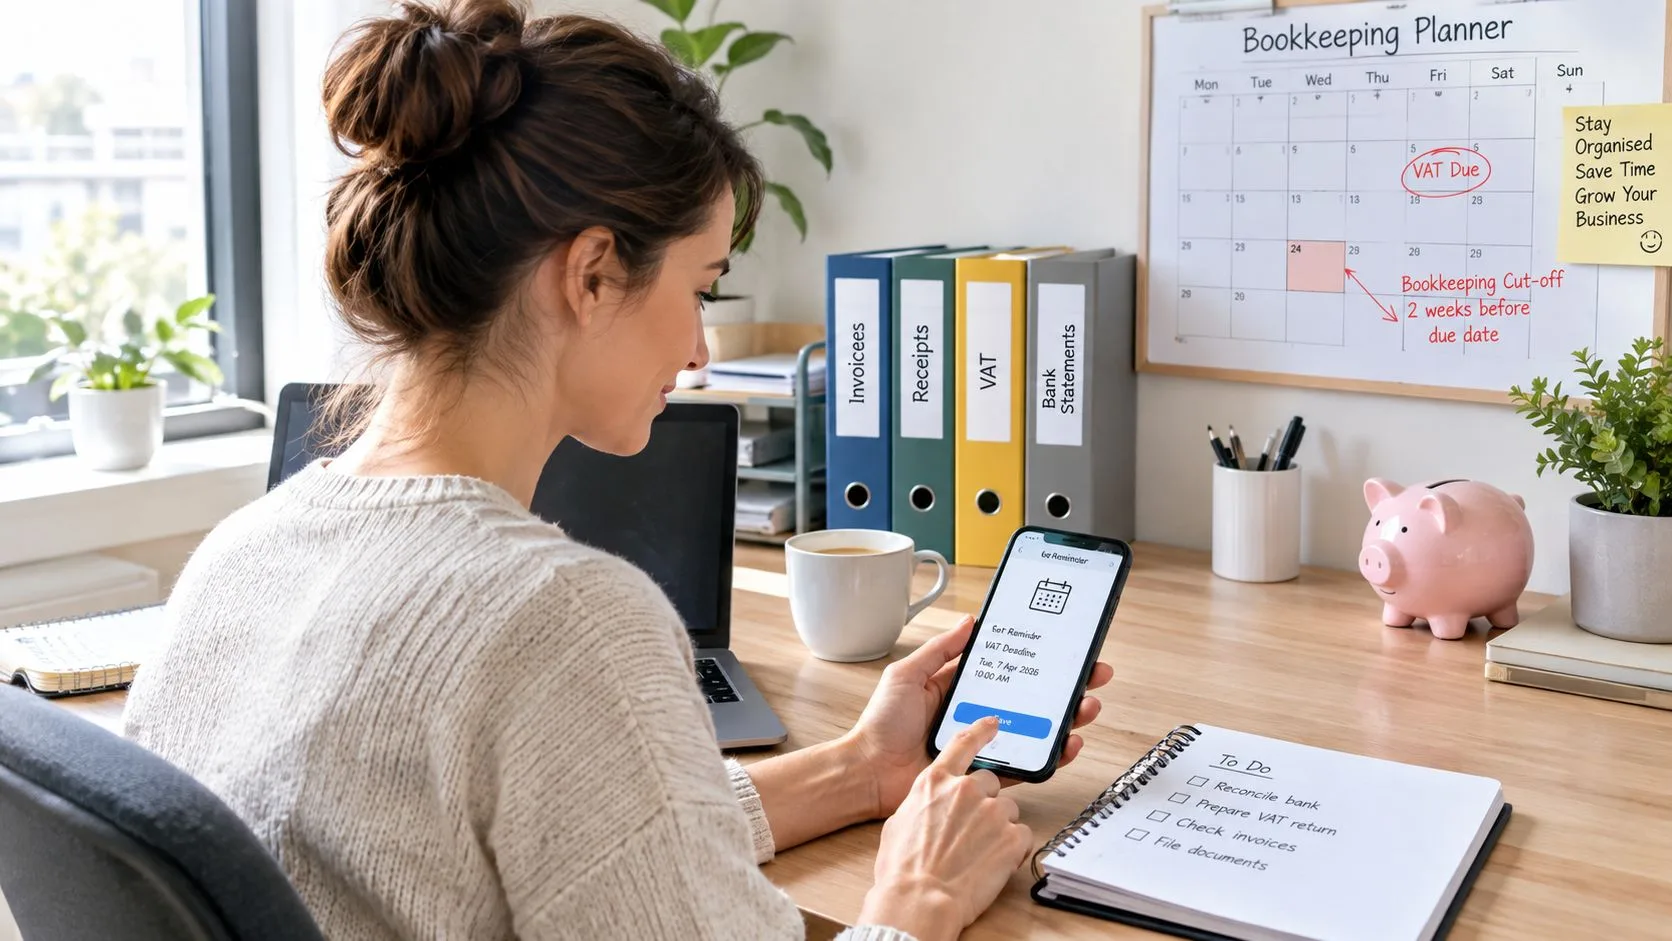
Use a staged reminder system rather than one alert on the due date:
- Early preparation: Set a reminder 21 days before the deadline to confirm that the bookkeeping period is complete and all key records are available.
- Review point: Set another reminder 14 days before to investigate unreconciled items, missing purchase invoices and unusual VAT movements.
- Final check: Set a reminder 7 days before to approve the return, confirm the payment amount and check that the payment method is ready.
- Same-day evidence: Create an alert for the deadline itself to confirm both HMRC submission and bank settlement.
Keep the VAT cash separate
VAT collected from customers isn't ordinary working capital. Move the VAT element of incoming receipts into a separate bank account or savings pot as soon as the cash arrives, where practical. This makes the amount visible and reduces the temptation to spend money that will later be owed to HMRC.
Your forecast should also treat the expected VAT reserve as unavailable for general business spending. If the business uses that reserve to fund stock, wages or expansion, the next return can become a cash crisis even when sales look healthy.
Check payment mechanics
HMRC may offer Direct Debit options for eligible VAT payments, but you still need to check the arrangement, the amount and the account details. Don't assume a Direct Debit removes the need to review the submitted return.
If you use online banking, confirm the settlement time for the payment type before the deadline. A transaction marked as sent isn't necessarily a transaction received by HMRC. For businesses using Xero or another cloud bookkeeping system, connect the VAT workflow to the bank reconciliation process and require a human review before filing.
Stewart Accounting Services is one option for SMEs that want support with VAT return preparation, bookkeeping and deadline management. The important point is to assign responsibility clearly, whether the task stays in-house or goes to an accountant.
Quick Reference Checklist and Final Takeaways
Use the table as a planning aid, then confirm the exact dates in your HMRC VAT account and VAT notices. The final two rows follow different payment arrangements, so their dates cannot be read like a standard quarterly return.
| VAT Due Date Quick Reference for 2026 | VAT Scheme | Period End | Submission Deadline | Payment Due | Penalty Trigger |
|---|---|---|---|---|---|
| Standard quarterly | Quarterly online | 31 March 2026 | 7 May 2026 | 7 May 2026 | Late return or late cleared payment |
| Standard quarterly | Quarterly online | 30 June 2026 | 7 August 2026 | 7 August 2026 | Late return or late cleared payment |
| Standard quarterly | Quarterly online | 30 September 2026 | 7 November 2026 (projected) | 7 November 2026 (projected) | Late return or late cleared payment |
| Standard quarterly | Quarterly online | 31 December 2026 | 7 February 2027 (projected) | 7 February 2027 (projected) | Late return or late cleared payment |
| Annual Accounting | Annual | Annual period end | Normally two months later | Instalments and final balancing payment follow scheme rules | Missed return or scheme payment |
| Payments on Account | Quarterly payment profile | Relevant quarter | Separate payment timetable | Last working day of months two and three of each quarter | Late instalment |
Projected deadlines are calculated using the one-month-and-seven-day rule. Always confirm the exact date in your HMRC VAT account.
Seven checks before filing
- Reconcile the bookkeeping: Confirm that bank, sales and purchase records agree.
- Verify the VAT balance: Review output VAT, input VAT, adjustments and unusual movements.
- Test the digital submission: Make sure your Making Tax Digital software is connected and ready.
- Confirm payment: Check the amount, bank account and expected settlement date.
- Review reminders: Keep both the internal working date and HMRC deadline visible.
- Obtain approval: Ask the responsible director or owner to review and approve the figures.
- Retain evidence: Save the submission receipt and payment confirmation with the VAT records.
The payment deadline and filing deadline may fall on the same date, but they create separate risks. A return can be submitted on time while the payment reaches HMRC late. The seven-day online timetable is not a payment grace period, so keep the VAT reserve ready before the due date.
For an approaching VAT date, identify the period end, apply the relevant rule and complete the reconciliation before the final week. Stewart Accounting Services can help prepare the return, check the payment and establish a repeatable cashflow process.
Need help staying ahead of your VAT due date? Book a practical review with Stewart Accounting Services, and bring your latest VAT notice, bookkeeping records and upcoming period end. You'll leave with a confirmed deadline, clear responsibilities and a payment plan that fits your business's cashflow.
Recent Posts
09 Oct, 2026
09 Oct, 2026
08 Oct, 2026
07 Oct, 2026
1 comment