
VAT Capital Goods Scheme: Rules, Thresholds and Examples
You recovered the VAT on a building or a fit-out, filed the return, and moved on. A couple of years later a floor is let on an exempt basis, a room becomes a private office, or a new activity in the same premises is exempt. The original claim can still have been right. The VAT Capital Goods Scheme asks whether that recovery still matches how you use the asset now.
What the VAT Capital Goods Scheme Does
The UK VAT Capital Goods Scheme is a long-term reconciliation, not a one-off claim. Under HMRC's Capital Goods Scheme guidance (Notice 706/2), it applies to land, buildings and civil-engineering works with VAT-exclusive capital spend of at least £250,000, individual computers or computer equipment at £50,000, and aircraft, ships, boats and other vessels at £50,000. Qualifying construction, refurbishment, fit-out, alteration and extension costs are caught too.
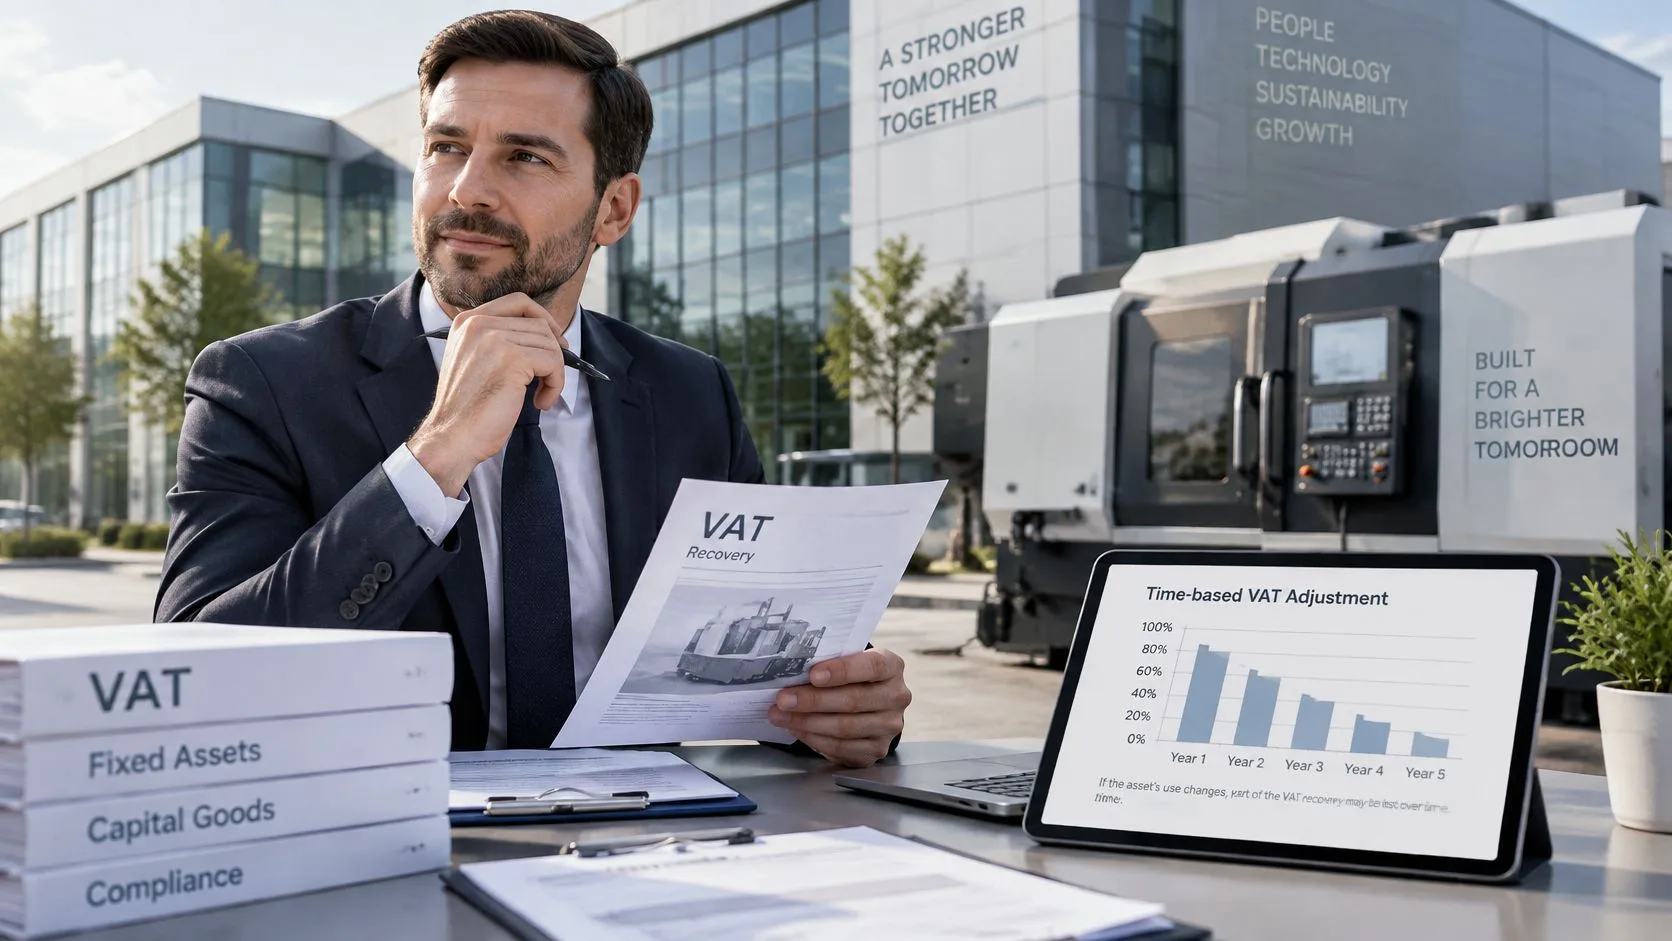
You do not lock the recovery on the purchase invoice. In each later interval you compare taxable use with the original recovery and make a payment or a claim. HMRC describes the mechanism as running for up to 10 years, which is why it affects major property whose use moves between taxable activity, exempt activity and non-business use. The adjustment period is 10 intervals for land, buildings, civil-engineering works and computers, and 5 intervals for aircraft, ships, boats and other vessels. Rules effective from 1 January 2011 extended adjustments to changes in non-business or private use and brought vessels at £50,000 into scope.
Treat the recovered VAT like a prepayment earned interval by interval. If you recovered £60,000 VAT in full on a £300,000 building, the 10-interval period puts £6,000 of that recovery in play each interval. If taxable use in one interval falls to 60%, £2,400 of that interval's slice is repaid. The first return can be correct and the later test can still move money back to HMRC.
A claim that was right, then a use that changed
You recover VAT in full on a workshop because every supply is standard-rated. Two years on, you let the upper floor as a dwelling, which is exempt. Nobody is saying the first return was wrong. The scheme measures the gap between that first recovery and the later mix of use.
Readers who also handle Australian GST can see how that system tracks input credits in GST credit guidance for Australian tradies.
The first recovery is a starting position, not a finished one. If you own a large asset whose use can shift, assume the scheme may still be open.
Which Assets Qualify and the Thresholds That Apply
Match the asset to a row before you read any further. Every threshold below is expenditure excluding VAT. The threshold works like a turnstile at the door. It decides whether the asset enters the scheme, not what happens once it is inside.
| Asset | Threshold before 29 July 2026 | Threshold from 29 July 2026 | Adjustment period |
|---|---|---|---|
| Land, buildings and civil-engineering works | £250,000 excl. VAT | £600,000 excl. VAT | 10 intervals |
| Individual computers and computer equipment | £50,000 excl. VAT | No longer covered | 10 intervals |
| Aircraft, ships, boats and other vessels | £50,000 excl. VAT | £50,000 excl. VAT | 5 intervals |
Two dates, two tests
HMRC's Revenue and Customs Brief 7 (2026) sets the reform at 29 July 2026. From that date, computers and computer equipment acquired on or after the effective date leave the scheme. The qualifying threshold for land, buildings and civil-engineering works rises from £250,000 to £600,000 excluding VAT. A property or construction project below £600,000 will generally fall outside the revised scheme for relevant acquisitions or works from that date. Aircraft, ships, boats and other vessels keep the £50,000 threshold after 29 July 2026.
The date you test is not the same for every asset. For land, HMRC applies the new £600,000 threshold to land acquired on or after 29 July 2026. For buildings and civil-engineering works, it applies to works acquired, constructed, refurbished, fitted out, altered or extended on or after that date. A refurbishment invoice dated after the change can sit in the new regime even when you bought the freehold years earlier.
Assets already inside the scheme under the previous £250,000 threshold stay there until their adjustment period ends. You can't stop the adjustments just because the threshold has moved. That is the ongoing use test in practice: entry was decided once, but the scheme keeps looking at the asset.
The £300,000 building that doesn't drop out
A qualifying £300,000 building project brought into the scheme before 29 July 2026 may keep generating adjustments. An equivalent project starting after that date would not meet the revised £600,000 threshold. Same bricks, two regimes. The file has to show the acquisition or works date, the value excluding VAT, and how many intervals are left.
For aircraft, ships, boats and other vessels, use £50,000 as the entry test on either side of 29 July 2026. The reform does not remove those assets from the scheme. A vessel bought for less than that stays outside. A vessel at or above it enters the five-interval cycle, and later changes in taxable use can still create a repayment even if the first VAT claim was correct.
Three checks on every line
Run this on each candidate before you add it to the register.
- Date: acquisition for land, and acquisition, construction, refurbishment, fitting out, alteration or extension for buildings and works.
- Value excluding VAT: compare it with the threshold that applied on that date, not with today's threshold.
- Nature of the spend: capital work on a scheme asset, not ordinary repairs you already treat as revenue.
If the spend is plant rather than the building itself, test it under the capital allowances rules as well. Our note on plant and machinery sets out how that classification usually works for SMEs.
How Adjustment Periods and Annual Calculations Work
Land, buildings, civil-engineering works and computers run for 10 intervals. Aircraft, ships, boats and other vessels run for 5. An interval is normally a twelve-month stretch tied to your VAT accounting, not the calendar year and not the anniversary you happen to remember. Confirm the start and end dates on the VAT account before you calculate anything.
Each interval owns an equal slice of the VAT you originally recovered. You don't re-forecast the whole life of the building every year. You score that slice against the use that happened.
The five steps
Record the VAT originally recovered and the acquisition date. Pull the figure from the return where you claimed it, and keep the invoice total excluding VAT beside it. The date decides which threshold regime the asset sits in, and the VAT figure is the only number you will split.
Divide that VAT into equal shares, one per interval. On a 10-interval asset, each interval carries one tenth. On a 5-interval asset, each carries one fifth. You do this once. Later changes in use don't resize the shares.
At the end of the interval, measure taxable use for that interval only. Use the same partial-exemption or apportionment method you use for the rest of the return. Floor area, time, or another fair method is fine if you apply it consistently and you can show the workings.
Compare that proportion with the original recovery. If you recovered 100% and this interval is 70% taxable, the gap is 30 percentage points against the original position. A fall usually means a payment to HMRC. A rise usually means a further claim.
Apply the gap to that interval's share and put it on the return. The adjustment belongs on the VAT return for the period in which the interval ends. Don't park it until the building is sold.
Adjustments follow actual use, not the business plan you wrote when you bought the asset. A forecast of “we'll stay fully taxable” doesn't protect a later exempt letting.
What to file at each interval end
Keep four things together: the taxable-use proportion, the method that produced it, the arithmetic on that interval's share, and the return it went into. If the next person preparing the return can't see those four, the adjustment isn't defensible.
Working Through a Pro-Rata Adjustment
Take a building acquired for £300,000 excluding VAT, with £60,000 of VAT recovered in full. Spread over 10 intervals, each interval carries a £6,000 share. These figures are simplified so you can see the mechanics. A live calculation uses the VAT on the actual invoices and your partial-exemption method for that interval. The partial exemption VAT calculation is the method most mixed-use businesses already run each year.
Use stays at 100% for two intervals, falls to 80% in interval 3 when part of the building is let on an exempt basis, and falls to 60% from interval 4 onward.
| Interval | Taxable use |
|---|---|
| Intervals 1-2 | 100%, no adjustment on the £6,000 share |
| Interval 3 | 80%, £1,200 repayable |
| Intervals 4-10 | 60%, £2,400 repayable in each interval |
| Whole period | Mixed, £18,000 total repayment |
Reading each band
Intervals 1 and 2 match the original 100% recovery, so the £6,000 share stays with you. Nothing goes on the return for the scheme.
Interval 3 drops to 80%. The gap is 20 percentage points of that interval's £6,000, which is £1,200 you repay. One exempt floor, not a change of the whole building, is enough to move the number.
Intervals 4 to 10 sit at 60%. The gap against the original 100% is 40 percentage points of £6,000, so £2,400 each interval. Seven intervals at that rate are £16,800. Add the £1,200 from interval 3 and the repayments total £18,000. You originally kept £60,000. You still keep £42,000, which is the VAT that tracks the taxable use you had.
When use recovers
Say taxable use returns to 90% in interval 9, against the 60% position of the intervals before it. Use has risen by 30 percentage points. Thirty per cent of the £6,000 share is £1,800, and that interval becomes a claim rather than a repayment. You measure each interval against the original recovery, not against last year's percentage, so don't chain the adjustments.
To rebuild this table for your own asset, pull five figures: VAT recovered at the start, number of intervals, taxable-use percentage in the original claim, taxable-use percentage in the interval just ended, and the return period that interval falls into.
Records That Keep Your Adjustments Defensible
A building bought in 2019 with VAT fully recovered can still produce a repayment in 2029. Nothing about the original claim was wrong. What changed is the use, and the only thing standing between you and a disputed assessment is a record that shows the interval, the taxable-use percentage and the figure that went on the return. Build that record as a register with one row per capital item.
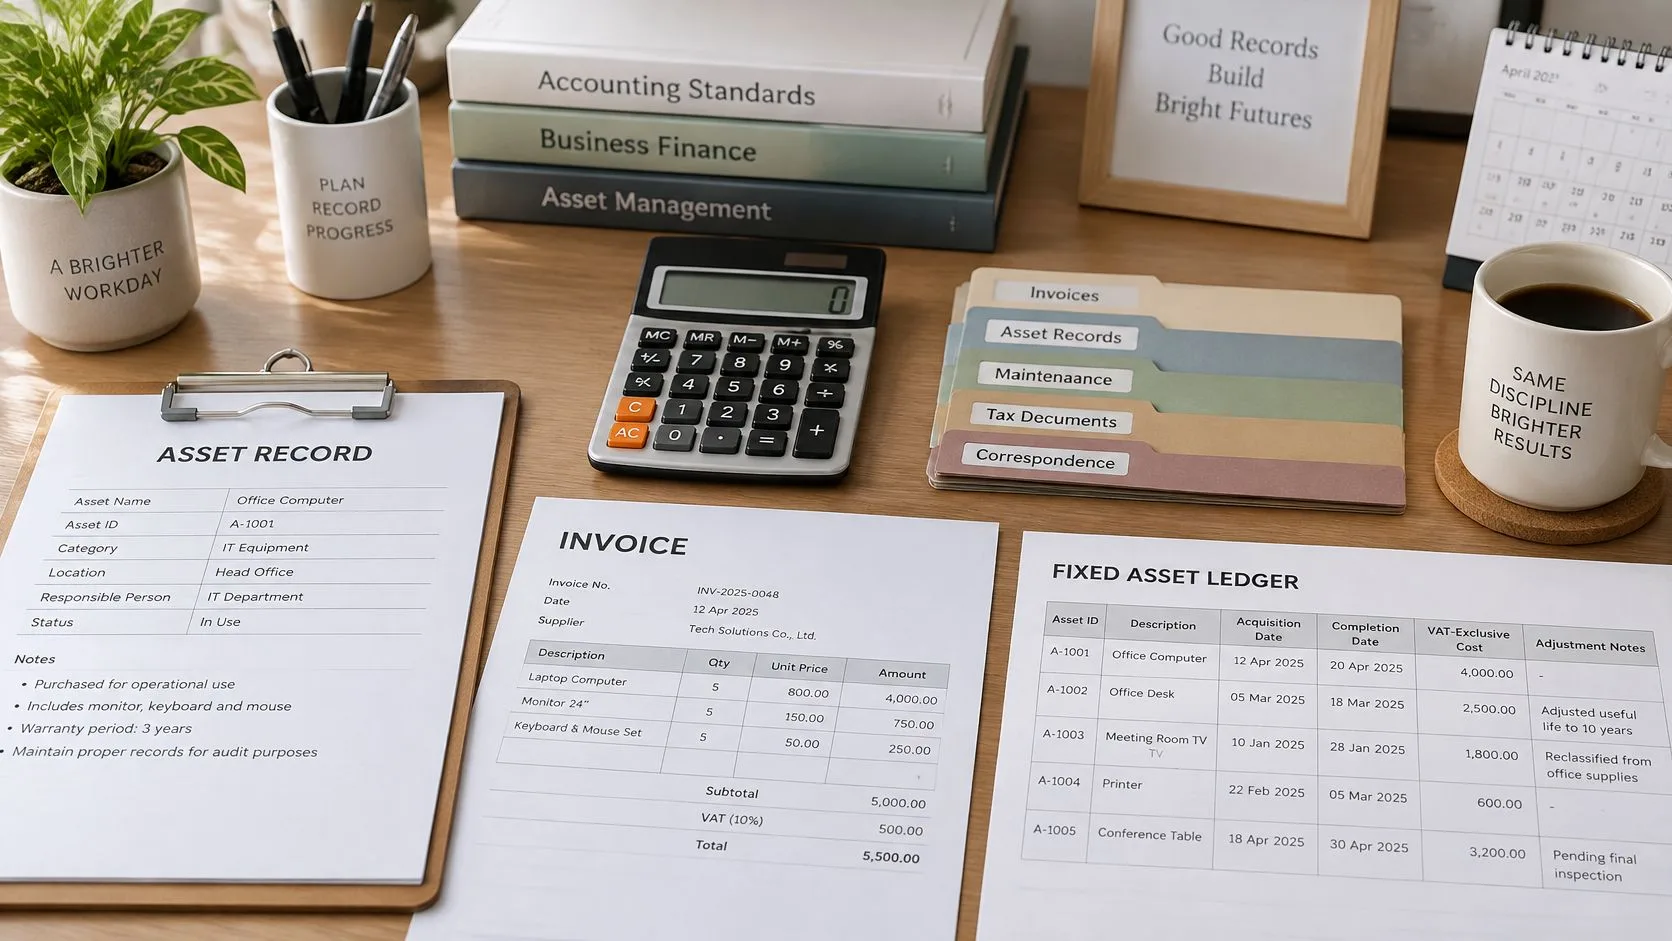
What belongs on the register
- Acquisition or completion date. The date picks the regime, so a purchase made near 29 July 2026 needs it written on the row rather than left in an email.
- Expenditure excluding VAT, and the VAT recovered. These two numbers give you the interval share. Divide the recovered VAT by the number of intervals and the register already holds the per-interval figure before you need it.
- Invoices for construction, refurbishment, fitting out, alteration and extension. A later fit-out is its own capital item with its own start date. File it as a separate row instead of merging it into the original purchase.
- Interval start and end dates. The adjustment goes on the return for the period in which the interval ends, so name that period on the row.
- A floor plan or room schedule. A taxable split of 80% is checkable only against a drawing. This is the evidence behind the percentage.
- Letting agreements for any exempt letting. The tenancy start date is the date exempt use began. Rent hitting the bank account does not prove that.
- Partial-exemption or apportionment workings for each year. Any percentage on a return has to trace back to a method someone else can repeat.
- The taxable-use percentage adopted on each VAT return. The next interval is measured against this figure, so it belongs on the same row as the share.
Treat each row the way you treat a meter reading: a dated figure that only means something when compared with the last one. An adjustment period runs for ten intervals on land, buildings and civil engineering works, and five on computers and computer equipment. A register that stops at the purchase invoice runs out of steam by interval four.
If you want a sense of how a VAT audit is sequenced, the Smart Classic Business Hub audit preparation checklist sets out the order in which documents are typically requested. Its questions are written for a different jurisdiction, so take the filing structure from it and the substance from the UK scheme rules.
Keep the whole register in one workbook or one cloud folder that the person filing the next return can open without hunting. Every row should let a stranger rebuild the calculation in a minute: original VAT, interval share, percentage applied, return period, and the repayment or claim that followed. When the percentage, the share and the return reference sit on different tabs, the adjustment gets missed and the correction turns up years later as a letter.
Common Pitfalls That Trigger Unexpected Repayments
A shop with a flat above it can pass every check at purchase and still produce a repayment six years later. The original VAT claim was correct. What changed is use. HMRC's Capital Goods Scheme guidance explains how a capital item moving into exempt or non-business use creates an adjustment. For qualifying land, buildings and civil-engineering works, the historic starting point is £250,000 excluding VAT. Individual computers and computer equipment historically qualify at £50,000 or more. You monitor the taxable-use proportion across the adjustment period, so a later shift in use can pull earlier relief back.
Four changes that move the percentage
- Part of the property becomes an exempt letting. A flat above a shop is the common case. Date the tenancy and remeasure floor area from the interval in which exempt use starts, not at the next year-end tidy-up.
- The company starts using part of the premises privately. A director's domestic use of a room is non-business use. Mark that area on the floor plan and take it out of the taxable percentage.
- A new exempt activity starts in a building you claimed on. Insurance, finance, health or education inside the same walls can shift the split. Run the partial-exemption calculation on the building itself, not only on overheads.
- The asset moves to non-business use. A property taken out of the business, or a vessel used privately, changes recovery. Make the change in the interval the use changed and keep the board minute or licence that shows the date.
The reverse-charge invoices
Qualifying construction work under the domestic reverse charge still belongs in the scheme, but those invoices need their own column. Check how the reverse-charge output tax should be treated against HMRC's Capital Goods Scheme guidance (Notice 706/2) before you calculate any adjustment. Folding it into capital VAT without that check can distort the adjustment, sometimes in your favour and sometimes against you. Record the invoice separately, reconcile the column, then run the annual calculation.
The wider mistake is treating the scheme as a one-off capital claim. Property plans, partial exemption, reverse-charge invoices and the annual return form one calculation. If the bookkeeping is split across a contractor and an in-house spreadsheet, a bookkeeping partner such as Hire Bookkeepers can keep the invoice coding consistent enough for the annual workings.
At every return, ask one question: has the taxable use of any scheme asset changed since the last interval?
Build Your Scheme Asset Register Before Your Next VAT Return
The register is built before the return is drafted. It is not a purchase file. It is a live schedule, one row per scheme asset, with columns for interval, taxable use and adjustment. A scheme asset can have been claimed correctly at purchase and still produce a repayment years later because the annual use test has moved. The register is how that move becomes visible before it reaches the return.
- List every property, computer, vessel and aircraft still inside its adjustment period. Record the acquisition date, the value excluding VAT and the VAT originally recovered. Put refurbishments and extensions on their own lines.
- Mark each line with the threshold it passed: the old £250,000 or £50,000 threshold, the revised £600,000 threshold for land, buildings and civil-engineering works, or no longer in the scheme. Computers acquired on or after the reform date go in the last group.
- Note the intervals still to run and the taxable-use percentage used in the current interval. Keep the percentage beside the figure it produces, so a later change can be traced.
- On each row, check exempt lettings, private space, a new exempt activity, and any reverse-charge construction invoice that must stay out of the adjustment. Those invoices belong in a separate column.
- Agree the register to the next VAT return before submission. The adjustment and the return narrative should name the same asset and the same interval.
A register of this size is manageable for a small company or a landlord with one or two buildings. It gets harder once refurbishments, extensions and mixed lettings sit on the same freehold. A blank asset register layout can speed the first pass, but the columns matter more than the design. Add the interval and use columns the scheme needs, then keep them populated at every return.
Stewart Accounting offers VAT return services that can check the register against the return. Stewart Accounting Services handles VAT returns for limited companies, landlords, sole traders and partnerships across Central Scotland and beyond. If an asset's treatment is unclear, ask about it before the next return goes in.