
Paying Capital Gains: A UK Tax Guide for 2026

You've sold a rental flat, a few shares, or part of a company holding, and now the money's in your account but the tax question hasn't gone away. The uncomfortable part of paying capital gains is that the sale can feel finished long before the reporting and payment deadlines do, especially if you're outside PAYE and no one has taken tax at source. For UK taxpayers, the practical job is simple in principle, but easy to get wrong in real life, because the right route depends on the asset, the completion date, and whether you still owe anything after allowances and reliefs.
First Things First Do You Owe Capital Gains Tax
A sale only becomes a capital gains tax issue if you've made a chargeable gain on a chargeable asset. In plain English, that usually means you've disposed of something that isn't covered by a broad exemption, and the disposal has produced a gain rather than a loss. The history matters too, because UK capital gains tax was introduced in 1965 and has become a permanent part of the tax position for business owners, landlords, and investors dealing with shares, business assets, and second properties Parliament briefing on the history of CGT.
What counts as a disposal
HMRC treats a disposal as more than just a straightforward sale. It can include selling, giving away, exchanging, or otherwise parting with an asset in a way that creates a taxable event. If you sold a second home, a portfolio holding, or business equipment with a gain attached, you're in the CGT workflow.
That's why a simple “I sold something” mindset isn't enough. You need to ask whether the asset is within the CGT rules, whether the gain is real after costs, and whether any relief applies before you assume tax is due.
The quickest self-check
A useful filter is this. If the asset is your main home, an everyday car, or something you disposed of at no gain, you may not have a CGT bill at all. If it's a property you didn't live in as your main home, shares, a business interest, or another investment asset, the capital gains process usually matters.
For landlords, the process often starts with a second property sale. If you want a plain-English primer alongside this guide, the internal explanation at what capital gains tax is for UK taxpayers is a useful companion, and capital gains tax tips for small investors also helps frame the issue from a property angle.
If the asset was sold, transferred, or otherwise disposed of, treat CGT as a reporting question first and a payment question second.
If that sounds like your situation, keep reading. If not, you may still need to track a disposal date and keep records, because CGT can sit in the background until the paperwork catches up.
Calculating Your Gain The Core Formula
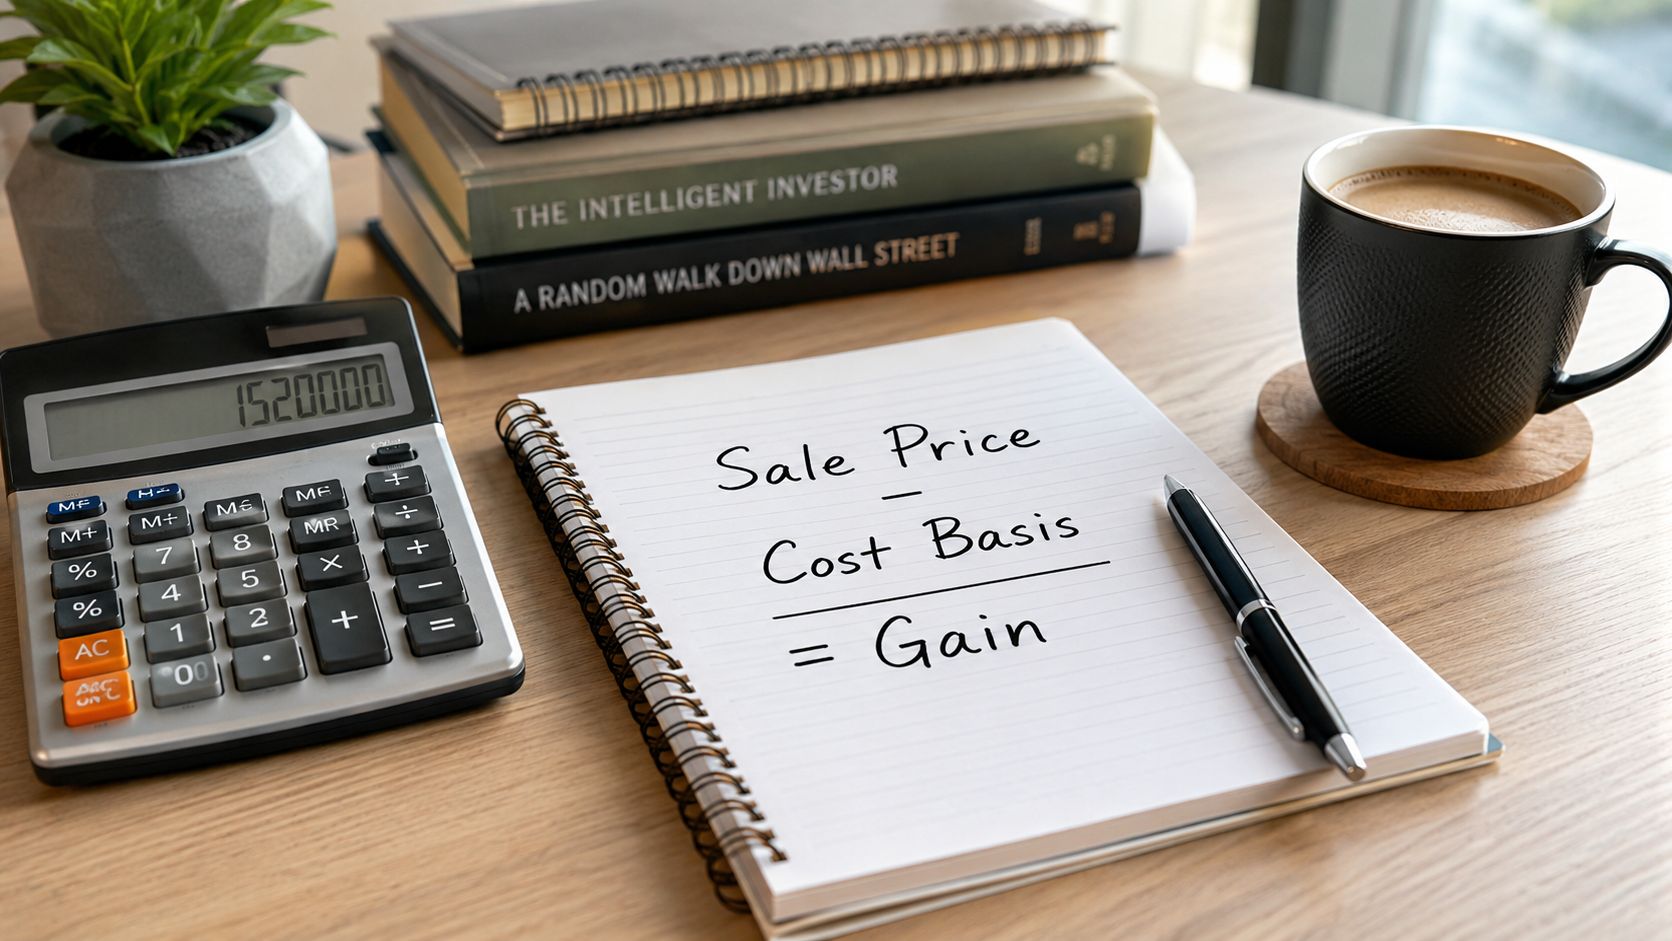
The core calculation is much less mysterious than many expect. The gain starts with the sale proceeds, then you subtract the original cost and the allowable transaction costs. What's left is your total gain before you apply losses, allowances, or reliefs.
What goes into the cost base
The purchase price is the starting point, but it's not the only number that matters. For UK CGT, you also need the genuine costs of buying and selling the asset, because those reduce the taxable gain rather than becoming separate deductions later.
Typical items to pull together are:
- Purchase price: what you paid for the asset when you bought it.
- Buying costs: legal or professional fees linked to acquisition.
- Selling costs: solicitor fees, agent fees, and similar disposal costs.
- Improvement costs: capital improvements that add value, not routine repairs.
The key distinction is between capital spend and maintenance. A fresh kitchen installed as part of a genuine improvement can be treated differently from an ordinary repair, while day-to-day running costs usually don't reduce the gain in the same way.
A worked landlord example
Take a landlord who sells a buy-to-let property. The sale proceeds are the starting point, then the landlord subtracts the original purchase price, the legal and selling costs, and any qualifying improvement costs. The resulting figure is the gross gain before reliefs and the annual exempt amount are applied.
That method is the same whether the asset is property, shares, or business assets. The numbers change, but the logic doesn't.
Keep every completion statement, invoice, and contract. Missing paperwork is one of the fastest ways to overpay CGT because people forget costs they were entitled to claim.
The most common mistake is to work backwards from cash received in the bank instead of from the tax rules. Cash proceeds are not the same thing as taxable gain, and the difference often sits in the costs people forget to include. If you want a practical referral point for the reporting side, the guide at how to report and pay capital gains tax is a sensible next read after you've gathered the figures.
Using Reliefs and Allowances to Reduce Your Bill
Once the gain is calculated, the next step is to strip out anything the law lets you exclude. That's where the annual exempt amount and the main reliefs matter most, because they can change a taxable gain into a much smaller one, or sometimes remove it altogether.
The allowances that matter most
The annual exempt amount is the threshold that keeps a portion of gains outside CGT each year. HMRC's reporting rules still matter even when the tax itself is low or nil, because a taxpayer can owe no tax but still need to report if the filing conditions are met HMRC CGT reporting rules.
For 2025/26, the UK capital gains tax picture for practical planning is as follows, and you should check your specific asset type before relying on a headline figure. The rates differ depending on whether the gain is from residential property or other assets, and the rate you pay can also depend on your overall income band.
| Item | Threshold / Rate |
|---|---|
| Annual exempt amount | Use the current annual exempt amount for the tax year, as set by HMRC |
| Residential property CGT | Taxed at the property rates set by HMRC |
| Other chargeable assets | Taxed at the rate linked to your income tax band |
| Reporting route for UK residential property | Report and pay within 60 days of completion |
| Reporting route for other assets | Usually Self Assessment in the following tax year |
If you want a concise summary of the allowance position for the year ahead, the note at the capital gains tax allowance for the 2026/27 UK tax year is worth checking alongside HMRC's own guidance.
Reliefs that can change the outcome
Private Residence Relief can reduce or remove CGT when a property has been your main home for the relevant period. Business Asset Disposal Relief can be relevant when an entrepreneur is selling qualifying business assets, shares, or a business interest. Those reliefs don't apply automatically, so the facts of ownership and use matter.
If the asset doesn't qualify, don't force the relief. That usually creates more work later when HMRC asks for support and the records don't line up with the claim.
The best tax result usually comes from matching the relief to the facts, not the facts to the relief.
The practical order is always the same. First, confirm the gain. Second, offset losses and allowances. Third, test reliefs. Only then do you arrive at the final tax bill.
How to Report and Pay Your Capital Gains Tax
The biggest source of confusion is not the rate, it's the route. UK residential property and other chargeable assets do not follow the same reporting timetable, and if you mix those up, you can miss a deadline even when the tax itself is straightforward.
The property route
For a UK residential property disposal, HMRC requires the gain to be reported and the tax to be paid within 60 days of completion HMRC reporting and paying CGT. That deadline runs from completion, not from when you first agreed the sale or when the money lands in your bank.
Many sellers get caught out. A property disposal can feel like a normal completion process, but the CGT filing sits on its own timetable and has to be handled separately. The more complex the sale, the more important it becomes to confirm the exact completion date and decide whether the return is required immediately.
The Self Assessment route
Other gains are usually reported through Self Assessment in the following tax year, unless HMRC's real-time CGT service applies in the specific circumstances. That route typically covers shares, business assets, and other non-property disposals. The key task is to match the disposal to the right reporting system before the deadline passes.
A common pitfall is assuming that no tax means no filing. That isn't safe. If the total taxable gains exceed the relevant allowance, a report can still be needed even where the final tax is low or nil HMRC reporting rules.
What you need before you file
Before you submit anything, pull together:
- Completion date: the date that drives the reporting deadline.
- Sale proceeds: the amount you received or are treated as receiving.
- Acquisition cost: what you paid for the asset.
- Costs and reliefs: anything that reduces the taxable gain.
- Supporting records: contracts, statements, invoices, and calculations.
If you want a practitioner-style walkthrough of the filing sequence, the internal guide on report and pay capital gains tax covers the practical mechanics of the return.
The payment issue matters as much as the form. For landlords and business owners outside PAYE, the tax is not automatically collected for you, so cash planning has to happen before the deadline, not after the filing. That's particularly important where the sale proceeds are being used to fund another purchase or to clear business borrowing.
Common Pitfalls and Strategic Tax Planning
The most expensive mistakes with CGT are usually simple ones. People miss the reporting deadline, forget allowable costs, claim a relief without keeping the evidence, or assume a sale will be taxed in the same way as salary or dividend income. That's why CGT planning is often more about process discipline than cleverness.
Mistakes that create avoidable tax
The first mistake is using the wrong reporting route. A UK residential property disposal does not wait for the following Self Assessment cycle if it needs to be reported within the property deadline. The second mistake is underclaiming cost. Sellers often omit legal fees, buying costs, or properly supported improvement costs, which leaves tax on the table.
The third mistake is treating CGT in isolation. OECD policy research notes that CGT outcomes are sensitive to timing, holding periods, and the interaction with other income, so the year you sell can matter as much as the gain itself OECD analysis of capital gains taxation. A dividend-heavy year, a bonus, or another disposal can alter the rate band that applies to the gain.
The timing decisions that really matter
A disposal in one tax year can produce a different result from the same disposal in the next year if your other income changes. That's why owners who take dividends, directors with fluctuating drawings, and landlords with multiple sales should look at the year as a whole, not just the individual transaction.
A gain rarely stands alone. Salary, dividends, and other disposals can shift the rate, so the right tax year can be just as important as the right relief.
That's also where professional support tends to earn its keep. A practitioner can compare sale timing, income mix, and relief eligibility before the disposal is finalised, rather than trying to repair the position after the deadline has passed. In some cases, firms such as Stewart Accounting Services can calculate capital gain liability for a second property and prepare the related return, which is useful when the numbers are more than a simple one-off sale.
For landlords who follow property-focused commentary, the JRG Property UK Ltd blog is another useful source of practical property sales context, especially when the tax issue sits alongside letting and exit decisions.
Your CGT Questions Answered
Inherited assets can still create a CGT issue later, but the tax usually arises on the eventual disposal rather than on inheritance itself. That distinction matters because the reporting question often comes back when the asset is sold, not when it is received. A sold inherited asset still needs the same gain calculation, record keeping, and deadline check as any other disposal.
Cryptocurrency gains can also fall within the capital gains framework if a disposal creates a taxable gain. The main practical point is to track what was acquired, what was disposed of, and when each disposal happened, because without a clean record you can't calculate the gain properly. The same discipline applies if you have several transactions over time, especially where the activity is spread across exchanges or wallets.
Losses are useful, but only if they're identified and reported correctly. If you've made previous losses, they may help offset current gains, but you still need the paperwork to support them. Without that evidence, the loss relief position becomes much harder to defend, and HMRC may not accept the offset you were expecting.
For anyone outside PAYE, the payment timing is what usually surprises them. A landlord or business owner can't assume the tax is collected automatically, and the due date depends on whether the sale is a UK residential property disposal or another asset. The HMRC reporting and paying capital gains tax guidance sets out the timing rules, and that is the point to check before cash from the sale is spent elsewhere.
If you're dealing with a property sale, multiple disposals, mixed income, or a claim for relief that isn't obvious, get the return reviewed before you submit it. A careful review should reconcile the disposal dates, reliefs, and payment timetable before HMRC's deadline becomes a problem. If you're at that point now, speak to Stewart Accounting Services and get the calculation and filing checked before the tax window closes.
Recent Posts
06 Oct, 2026
04 Oct, 2026