
Financial Due Diligence Checklist: A 10-Point UK Guide

Before you buy or sell a business, the numbers can look clean and still hide the problems that matter. A slick Xero file, a tidy management pack, and a confident seller do not replace proper scrutiny. The right financial due diligence checklist helps you test whether profit is real, cash is reliable, and the balance sheet can support the price you're about to agree.
That matters most for UK SMEs, where the story often starts with cloud accounting, not a big finance team. You might be looking at a growing limited company, a property business, or a trade group that's moved from spreadsheets into Xero and now needs a sharper lens on cash, tax, and working capital. Buy-side diligence is about protecting your downside, sell-side diligence is about removing surprises before a buyer finds them.
The practical approach is simple. Ask for the right documents, compare them properly, and focus on the items that change valuation, not just the items that fill a data room. If you want a broader modelling context alongside due diligence, DigiParser helps with real estate models, but the core of the job is still disciplined financial checking. A good adviser won't drown you in paperwork. They'll show you where the risk sits and what to do about it.
1. Historical Financial Statements Review for the Last Three to Five Years
Start with the longest clean view you can get. For a UK financial due diligence checklist, that usually means three to five years of historical accounts, because that is long enough to show whether revenue, margins, debt, and cash flow are consistent or just boosted by one unusual year. That lookback also fits common due diligence practice for testing earnings quality, debt, and cash conversion.
Ask for the profit and loss account, balance sheet, and cash flow statement for each year, then line them up against tax filings and management accounts. If the business runs on Xero, the comparison is often easier because you are working from one accounting record rather than several disconnected spreadsheets. Consistency matters here. A business that has changed accounting policies, chart codes, or balance sheet treatment every year can look steadier than it really is.
Practical rule: if the seller cannot explain the movement in debtors, creditors, or gross margin across each year, the files are probably showing you more than the narrative is.
A well-run SME can still carry distortions. A one-off insurance receipt, a large bad debt write-off, or an owner-led restructuring charge can distort underlying performance, so those items need to be separated out rather than averaged into the normal run rate. For a property landlord, the same discipline applies to rent, maintenance, and void periods. For a trading company, the question is whether the move from six figures to seven figures came with better cash conversion, or just heavier working capital strain.
For buyers who want the numbers tied into a live forecast, our cash flow forecasting guidance shows how to build that bridge from historic performance to forward planning. If the target's finance process is already being automated, the guide to automating finance with AI is useful context for understanding how quickly reporting can improve, and where automation still needs human review.
What to request first
- Annual accounts and management accounts: request the full three to five years, not just the latest statutory pack.
- Tax returns and supporting schedules: compare them against reported profits to catch reconciliation issues early.
- Accounting policy notes: document any changes in revenue recognition, depreciation, or inventory treatment.
- One-off adjustments: ask the seller to identify exceptional items and explain whether they will repeat.
If the target only has statutory accounts, ask for management accounts to fill the gap. A buyer needs enough history to understand trend, seasonality, and the working capital cycle before moving any closer to completion.
2. Cash Flow Analysis and Liquidity Assessment
Profit does not pay suppliers, wages, or HMRC. Cash does. In a UK SME acquisition, that is the part of the financial due diligence checklist that tells you whether the business can keep trading comfortably, or whether the headline profit is masking pressure in the bank account. A proper review should reconcile reported profit to operating cash flow, then test the quality of working capital through receivables collectability, creditor pressure, debt terms, and revenue concentration.
In Xero or another cloud accounting system, cash flow is often the first place where strain shows up. A construction SME can report healthy contract margins and still burn cash because customers pay slowly while suppliers expect quicker settlement. A contractor with irregular project timing can look acceptable across a full year and still run short in a weak month if a pipeline delay lands at the wrong time. The question is whether the business can fund the next quarter without relying on the overdraft as a habit.
Use cloud reports alongside a live forecast, not a spreadsheet that has sat unchanged since the year end. In practice, the strongest view comes when forecast assumptions are linked to aged debtors, expected supplier runs, and actual bank feed data. For a practical forecasting structure, see Stewart Accounting Services' cash flow forecasting guidance. If finance has already been automated, the guide to automating finance with AI is useful context for seeing where reporting can speed up and where human review still matters.
Cash stress usually turns up in the debtor book before it shows in the profit and loss account.
Signs that deserve a closer look
A buyer should pay attention when customers are taking longer to pay than their terms suggest, because that usually means the working capital cycle is stretching. The same applies when the company is delaying supplier payments to protect cash, or when seasonal trading creates a sharp build-up in funding needs before revenue catches up. Thin liquidity is another warning sign, especially where the bank balance leaves little room for delayed receipts, VAT payments, payroll, or unexpected outgoings.
The right approach is to set a realistic cash reserve, model both strong and weak trading, and check whether the company's overdraft or loan facilities match its trading rhythm. Growth can absorb cash before it creates it. That is normal, but it still has to be funded properly.
3. Tax Compliance and Exposure Review
A buyer checking a UK SME often finds that tax risk sits just beneath a tidy set of management accounts. The headline profit may look acceptable in Xero, yet the core issue is whether VAT, PAYE, corporation tax, and filings to HMRC have all been handled in line with what was reported. Independent UK due diligence guidance highlights the need to reconcile historical financial statements with tax returns, review tax compliance and contingencies, and test the points where tax and accounting diverge.
The first job is to ask for the returns, workings, and supporting schedules that sit behind the filed numbers, then compare them properly against the accounting records. Cloud bookkeeping makes life easier, but it does not remove errors. VAT cut-off issues can still arise around month-end invoices, director loan accounts can drift if they are not reconciled regularly, and payroll postings can be coded correctly in the ledger while still creating a mismatch in the tax treatment. In a small property business, expenses can be claimed in the wrong place. In a contractor-led company, CIS history can need a proper review. In a limited company with steady profits, the accounting result may still not match what HMRC expects once adjustments are considered.
Areas that deserve scrutiny
- Corporation tax position: check the filed returns, payment record, and any open correspondence or outstanding queries.
- VAT treatment: confirm that output tax, input tax, and cut-off entries have been applied consistently, especially where invoices straddle period end.
- Payroll and directors' pay: review PAYE, dividends, benefits, and whether any payments have been coded or classified incorrectly.
- Related party items: look for private spending, reimbursements, or loans that have been run through the business without clear support.
A clean set of accounts is helpful, but it is not enough on its own. The question is whether the tax file is tidy because the business is well controlled, or tidy because the issues have not yet been challenged. A seller may want the diligence kept light so the transaction keeps moving. That can work where the structure is simple and the records reconcile cleanly. It becomes a problem when add-backs recur, a director loan balance moves around without a clear explanation, or personal costs have been mixed into the books with little documentation.
The practical trade-off is speed against certainty. If the tax position is straightforward, a targeted review may be enough. If the returns, reconciliations, or director account do not hang together, the buyer should slow down and bring in a specialist adviser such as Stewart Accounting Services before the deal gets too far along.
4. Accounts Receivable and Debtor Quality Assessment
A buyer can be shown strong turnover and still inherit a weak cash position if the debtor book is sloppy. For UK SMEs that invoice on credit terms, accounts receivable deserve a close look because the true value lies in what will be collected, not what has been raised on paper. That is particularly true where a business depends on a handful of repeat customers, or where overdue balances have become part of normal trading.
Start with the aged debtor report and then work customer by customer where the balances matter. A service company can post healthy sales while invoices drift unpaid because credit control is too relaxed. A contractor may report good revenue, yet one disputed project can lock up cash for months and create pressure on working capital. If one customer accounts for a large share of the debtor book, the risk is commercial and financial at the same time, because any delay in payment affects collections, valuation, and day-to-day liquidity.
Practical rule: if the debtor list contains invoices old enough to be argued about rather than collected, treat part of the profit as uncertain until the evidence says otherwise.
Questions to ask the finance team
- Credit policy: who sets credit limits, and how often are they reviewed in practice?
- Collection pattern: are customers slipping later each month, even where sales are growing?
- Bad debt provisioning: is the provision based on actual history, or on hopeful assumptions?
- Concentration risk: does one customer dominate the debtor book as well as the revenue line?
A cloud-accounting platform like Xero only helps if it is used properly. Automatic reminders, clear payment terms, and a weekly review of overdue balances are signs that the business is managing cash rather than just recording it. If the system is there but nobody checks the dashboard, the issue is discipline, not software. For a deeper look at how to judge the quality of the debtor ledger, see our guide to inventory valuation methods for the related control mindset around assets and recoverability.
The trade-off is growth against control. New customers often come with looser credit in the early months, and that can be acceptable if the business has the systems to tighten terms later without harming sales. If it cannot, the debtor book may be masking part of the acquisition risk. In that case, a realistic doubtful debt provision matters more than a tidy sales report.
5. Inventory and Fixed Assets Valuation
A buyer walking into a small warehouse, workshop, or retail stockroom should not accept the balance sheet at face value. Stock can look like an asset and still behave like a drag on cash, especially where lines move slowly, items age in storage, or the business has been too relaxed about write-downs. In retail, manufacturing, and some service businesses, inventory, tools, and equipment need a proper reality check before anyone relies on the figures in the accounts. A due diligence review should test how inventory is valued, whether obsolescence has been allowed for, and whether fixed assets still exist, still work, and are still needed.
For a retail SME, the question is practical. What is on the shelves, what can be sold without heavy discounting, and what has already gone stale? For a manufacturer, the focus shifts to raw materials, work in progress, and finished goods, because value changes as stock moves through the production cycle. For a property business, the issue may be capital improvements, fit-out costs, or plant and machinery that have been treated too casually in the books. If the stock count and the accounting record do not agree, the balance sheet is only partly useful, and the gap needs explaining before completion.
Focus points that change value
- Physical count: reconcile the ledger to what is on site, and ask whether the count was independent or accepted from management.
- Slow-moving items: identify goods that are unlikely to convert to cash without discounting, especially where seasonality or model changes have left old lines behind.
- Asset register quality: check acquisition date, cost, depreciation, and disposals, then compare the register with what is physically in use.
- Usefulness of equipment: determine whether underused kit should be sold, leased, repaired, or written down before the buyer inherits the problem.
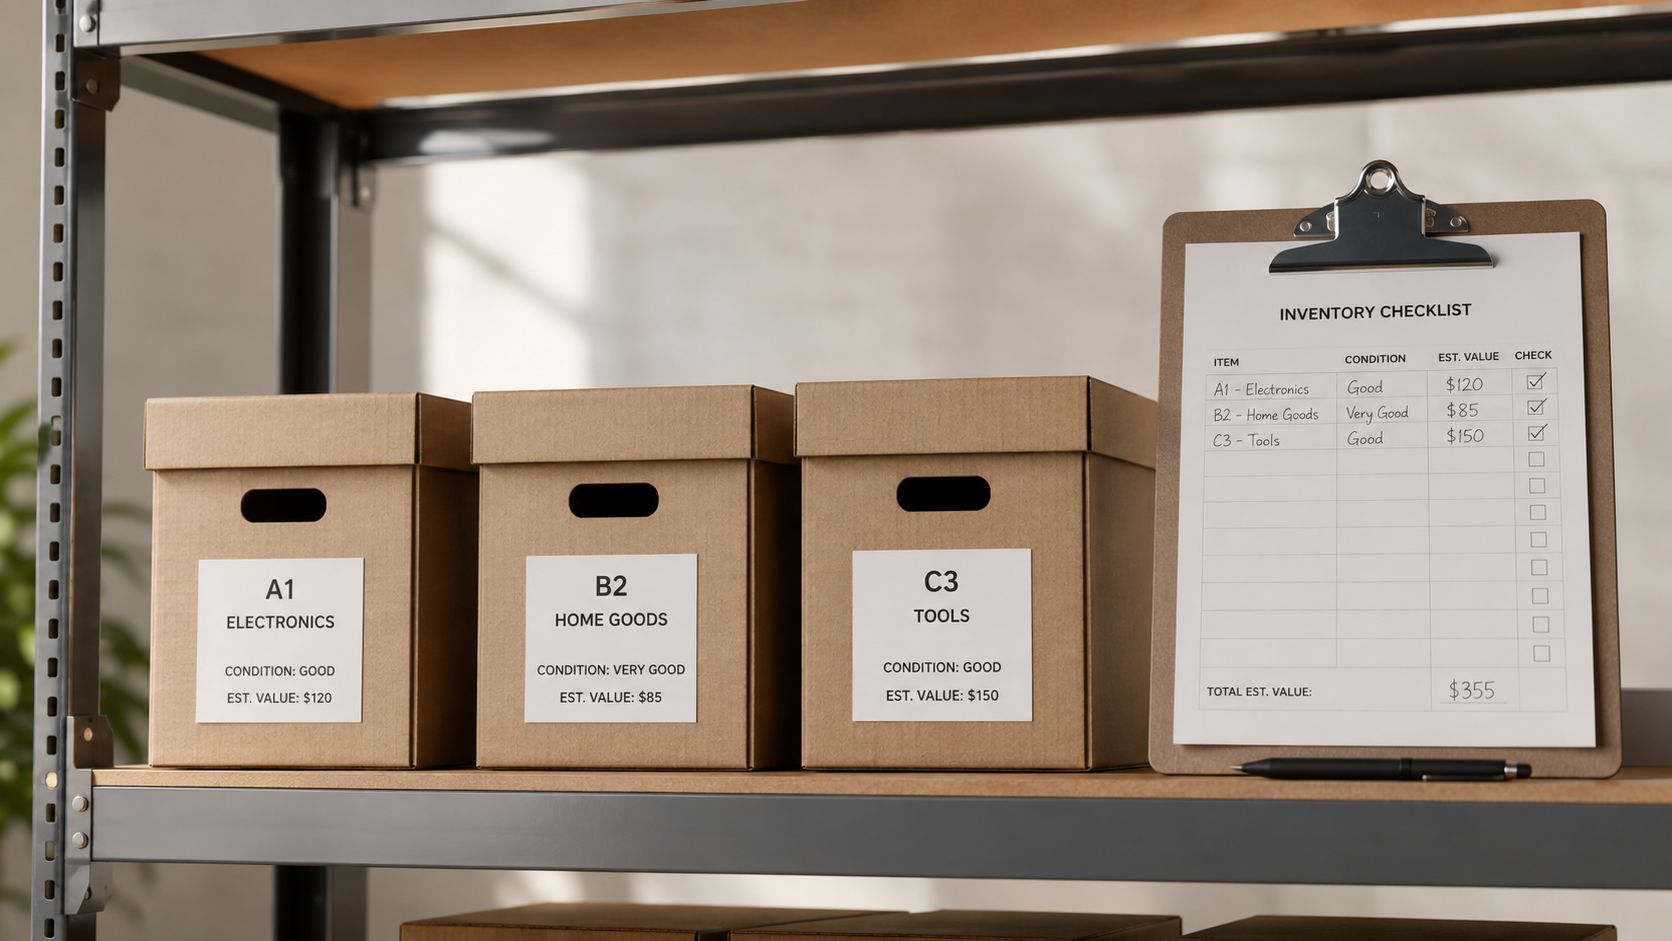
The hard part is judgment. A warehouse full of stock is not automatically valuable if half of it is obsolete, damaged, or mixed by age in a way that makes selective sale difficult. Fully depreciated equipment can still be useful, but only if it has been maintained and is not likely to need immediate replacement after completion. That turns a fixed asset review into a cash planning exercise as well as an accounting one, because replacement spending after acquisition often lands on the buyer faster than expected.
Where inventory is a meaningful part of the business, the finance team's costing method also needs testing. Small coding errors in cloud accounting can distort cost of goods sold, which then flows through to margin, stock value, and the price you should be willing to pay. If you want a practical reference point on how stock values can move depending on method and treatment, see Stewart Accounting Services' inventory valuation guidance.
6. Liabilities, Debt and Contingent Liabilities Analysis
A business can look healthy on the face of the management accounts and still carry obligations that change the deal very quickly. Debt covenants, lease commitments, pension issues, tax exposure, and unresolved claims all affect what a buyer inherits. For an SME buyer relying on Xero or another cloud package, the key is to separate what is already booked from what may surface later through lender letters, solicitor correspondence, or a director's memory.
Start with the balance sheet items you can see, then check the commitments that sit off it. Bank loans, overdrafts, asset finance, trade creditors, tax liabilities, and leasing commitments should all be listed clearly, with repayment terms, security, and any personal guarantees attached. After that, look for guarantees, legal claims, warranty exposure, and regulatory correspondence. If the records are tidy, some of this will be obvious. If they are not, expect a slower review and more follow-up with the seller.
What tends to change the price
- Debt covenants: limits on capital spend, distributions, or extra borrowing can restrict what the buyer can do after completion.
- Lease and hire commitments: the monthly commitment may be small in the accounts but still heavy in cash terms.
- Tax contingencies: VAT, corporation tax, or payroll disputes can turn into price chips, retention requests, or warranty concerns.
- Pension and employment claims: long-trading businesses can carry issues that do not show up cleanly in the management numbers.
The practical trade-off is simple. Push too hard too early and the seller may feel interrogated. Ask too little and you miss the items that alter valuation. A sensible adviser quickly sorts the routine from the risky. If the debt schedule ties to the bank statements, lender correspondence is consistent, and no unusual guarantees appear, the review can stay focused. If there are side agreements, director guarantees, or balances that do not reconcile, slow the process down and ask for the underlying paperwork.
If a liability could land on you after completion, treat it as debt until you have checked otherwise.
Contingent liabilities are the point where legal and specialist input often pays for itself. An accountant can identify the exposure, but a legal adviser or pensions specialist should confirm how likely the claim is and what the funding position really means. A buyer who skips that step often discovers the problem only after completion, when the purchase price is already committed.
7. Related Party Transactions and Conflicts of Interest
A buyer often spots related party issues first in the numbers, not in the narrative. A director's loan, a rent charge to a sister company, or regular payments to a family-owned supplier can all change how the business should be valued. In a financial due diligence checklist, those arrangements need to be identified early, because they can distort profit, mask support from the owner, or create a conflict that continues after completion.
A practical review starts with the obvious question. What would the accounts look like if the business were dealing entirely at arm's length? That is the standard I use when reviewing an SME acquisition for a buyer. If the company is paying below-market rent, using a connected entity for free services, or settling personal costs through the business bank account, the reported earnings are not the same as transferable earnings. Those differences matter when you are deciding what the business is really worth, and what it will cost to run once the seller is gone.
The checks should follow the cash as well as the paperwork. Look at who receives money from the company, who owes money back, and whether those balances move in a way that makes commercial sense. A clean set of nominal codes in Xero does not always mean the transaction is clean in substance, especially where the owner has used multiple entities or mixed business and private spending across accounts.
What to test carefully
- Connected-party register: identify directors, family members, and associated entities, then compare the list with supplier and customer ledgers.
- Loan balances: check whether advances are formal, repayable, and properly recorded, and whether interest or repayment terms have been applied consistently.
- Asset transfers: confirm the price and terms make commercial sense, especially where equipment, vehicles, or property have moved between connected businesses.
- Personal expenses: make sure they're separated from business costs, then normalise EBITDA where private spending has been running through the books.
One area I focus on is whether the arrangement would survive a change of ownership. If a parent company provides admin support, if a related landlord offers a favourable lease, or if a director draws value through a loan account instead of salary, the buyer needs to know what happens on day one after completion. The accounts may still be accurate, but the trading model may not be repeatable.
There is a trade-off here. SME businesses often rely on the owner's family, other group companies, or informal support to keep things moving. That is normal. The issue is whether the benefit is temporary, whether it is properly disclosed, and whether the buyer will need to replace it with paid-for services after completion. In a Stewart Accounting Services review, this is often where we separate a tidy set of records from a commercially reliable profit figure.
8. Revenue Recognition and Sales Quality Analysis
A buyer should test revenue quality before taking the reported turnover at face value. In a UK SME review, I would want to see when revenue is recognised, what the contract says, and whether the sales shown in the accounts were earned in the period. I would also reconcile the headline figures to VAT returns, review cut-off around the year end, and check for signs that revenue has been brought forward to make the numbers look cleaner than they are.
The risk is highest in service businesses and project-led SMEs using cloud accounting tools such as Xero. A business can raise invoices early, post income before work is complete, or push delivery into the next period while still recording the sale. It can also lean on a single large order that flatters the year but does not reflect the normal run rate. The seller may talk about pipeline, but the buyer needs to know whether that pipeline is supported by signed contracts, agreed milestones, or just hopeful forecasting.
A practical review starts with the documents, not the management commentary.
- Cut-off timing: check whether invoices and credit notes sit in the correct period, or whether year-end has been managed to flatter revenue.
- Contract terms: confirm whether the contract allows upfront recognition, stage-based recognition, or only recognition after delivery.
- Returns and allowances: look for discounts, disputes, rebates, and post-sale adjustments that reduce the quality of reported sales.
- Customer dependence: test whether growth comes from repeat business, or from a few one-off wins that are hard to replace.
The policy matters, but so does behaviour around it. If management is rewarded on reported sales, there can be pressure to recognise income aggressively. That does not automatically mean the accounts are wrong, but it does mean the buyer should ask for evidence. For project work, that means milestone certificates, signed completion records, and clear handover notes. For service businesses, it means signed scopes, acceptance evidence, and correspondence that shows the work was completed. For product businesses, dispatch records, returns data, and post-sale issues matter just as much as the invoice.
Revenue booked too early can distort valuation, create tax exposure, and leave the buyer with cash that has not yet been earned.
Consistency is the discipline that separates a tidy policy from a credible one. Once the revenue recognition method is set, it should be applied the same way each month, not adjusted to suit the reporting period. If the business has grown quickly, check whether sales quality kept pace with that growth. Strong turnover with weak control is a common reason acquirers slow down, reprice, or ask for a specialist review from Stewart Accounting Services.
9. Key Performance Indicators and Financial Metrics Tracking
A buyer who only looks at profit is missing how the business performs. In an SME acquisition, the useful metrics are the ones management can review every month, challenge in Xero, and explain without a slide deck full of noise. For a cloud-based finance function, the aim is not more dashboards. It is a small set of measures that show whether sales quality, cash generation, and overhead control are moving in the right direction.
For a growing UK SME, the figures should be simple enough for an owner-manager to trust and hard enough to manipulate only with effort. Gross margin matters when supplier costs shift. EBITDA still matters because it shows underlying profitability, but it should be tested against cash conversion. If a business grows quickly while debtor days stretch and stock builds up, the headline profit is doing less work than the bank balance. A property business may need rental yield, void periods, and maintenance spend reviewed together. A service business may get more value from customer acquisition cost and lifetime value than from a busy-looking sales pipeline.
A practical KPI approach
- Pick a small set: track the measures that drive decisions, not every figure available from the system.
- Keep the definitions fixed: if the calculation changes every month, the trend becomes harder to trust.
- Use the dashboard properly: if the report sits in Xero, management should review it and act on it.
- Benchmark sensibly: compare against your own history first, then against the market where that comparison helps.
A good KPI pack should flag drift before it turns into a valuation problem. If gross margin is slipping, the buyer should ask whether the issue sits in pricing, supplier terms, or a change in mix. If cash conversion is weakening, the debtor ledger or stock build usually explains why. If EBITDA rises while cash stays flat, the working capital story needs a closer look. In practice, that is where specialist support such as IT support for financial accounts can help if the data is there but the reporting is not reliable.
The trade-off is always detail versus action. Too many measures leave owners and managers chasing noise. Too few miss the warning signs that matter during diligence. Most SMEs do better with a disciplined monthly set of KPIs, a short commentary that explains what changed, and a clear review of segregation of duties, as covered in this guide to segregation of duties. That gives a buyer enough evidence to judge whether the numbers are being managed properly, without getting lost in a pack nobody reads.
10. Accounting Records Quality and Internal Controls Assessment
A buyer can only trust what the finance records can support. If the bookkeeping is messy, the valuation work becomes less dependable, because you spend more time testing the numbers than understanding the business. For an SME using Xero or a similar cloud platform, I look first at whether the ledger is tidy, whether approvals are clear, and whether there is enough separation of duties to reduce error and fraud risk.
Cloud software helps, but it does not fix weak process on its own. Xero can make bank reconciliation, approval flows, and audit trails easier to manage, yet those controls only work if staff follow them consistently. If one person raises invoices, approves payments, and posts journals, the control environment is too loose. If bank reconciliations are left until month end is already closed, management is reacting too late. If payroll is not checked against the approved headcount, mistakes can sit in the system for months. Good practice also means checking whether the finance function has the right IT support for financial accounts so the reporting setup does not become the weak point.
What a buyer should ask for
- Bank reconciliations: ask for the latest reconciliations and confirm they have been reviewed, not just prepared.
- Invoice support: check that larger payments have an approval trail, a contract, or another piece of evidence behind them.
- Payroll checks: compare the payroll file to the actual workforce and look for leavers, starters, or duplicated entries.
- Asset verification: test whether inventory and equipment on the books exist in practice, and whether any obsolete items are still being carried at value.
The point is not to create bureaucracy. The point is to show that the numbers will still stand up after completion. If the business has had duplicate payments, weak invoice authorisation, or signs of employee theft, those issues need to be understood before anyone signs. In smaller owner-managed businesses, that often means bringing in an independent review rather than relying on tidy-looking accounts alone.
For a practical control review, see Stewart Accounting Services' guidance on segregation of duties. A proper review here can cut down on follow-up questions later and show where the reporting process is dependable, and where it still depends too heavily on one person.
10-Point Financial Due Diligence Comparison
| Item | Implementation complexity | Resource requirements | Expected outcomes | Ideal use cases | Key advantages |
|---|---|---|---|---|---|
| Historical Financial Statements Review (3-5 Years) | Moderate–High (depends on record quality) | 3–5 years audited/statutory accounts, accounting analyst, benchmark data | Trend identification, baseline financial health, inputs for valuation | M&A, lender due diligence, growth planning | Establishes financial trajectory; highlights one-offs; validates earnings |
| Cash Flow Analysis and Liquidity Assessment | High (transaction-level data + modelling) | Bank statements, cash forecasts, CFO/analyst, forecasting tools | Cash runway, funding gaps, working capital requirements | Working capital planning, financing decisions, seasonal businesses | Reveals true liquidity; identifies funding constraints; improves cash forecasting |
| Tax Compliance and Exposure Review | High (complex regulations) | Tax returns, payroll records, VAT filings, tax specialist/advisor | Compliance status, exposures, tax planning opportunities | Pre-acquisition reviews, year-end planning, multi-entity businesses | Prevents penalties; identifies savings; ensures statutory compliance |
| Accounts Receivable and Debtor Quality Assessment | Moderate | Aged receivables ledger, customer credit data, AR analyst/tools | Revenue quality, collection risk, concentration insights | Credit risk assessment, cashflow improvement, lending support | Identifies concentration/bad debt risk; improves collections; supports forecasts |
| Inventory and Fixed Assets Valuation | High (physical counts, impairment testing) | Inventory records, fixed asset register, physical verification, specialists | Accurate asset values, obsolescence detection, corrected depreciation | Retail, manufacturing, asset-heavy businesses, valuation exercises | Ensures balance sheet accuracy; uncovers obsolete stock; informs valuation |
| Liabilities, Debt and Contingent Liabilities Analysis | Very High (legal and financial complexity) | Loan agreements, legal counsel, pension/lease data, auditors | Leverage profile, covenant risks, contingent exposure identification | M&A, refinancing, growth financing, covenant monitoring | Reveals hidden obligations; informs refinancing and covenant strategy |
| Related Party Transactions and Conflicts of Interest | Moderate | Transaction records, related party register, valuations, tax/valuation advisor | Arms‑length verification, adjusted profitability, disclosure clarity | Family businesses, closely-held companies, pre-sale due diligence | Improves transparency; prevents hidden subsidies; supports tax compliance |
| Revenue Recognition and Sales Quality Analysis | High (contract review, accounting standards) | Customer contracts, sales ledger, legal/accounting review, IFRS/GAAP expertise | Verified revenue quality, detection of aggressive recognition, forecast reliability | Project-based firms, companies with large/one-off sales, investor due diligence | Validates earnings sustainability; uncovers timing risks; supports valuation |
| KPI and Financial Metrics Tracking | Low–Moderate | Monthly financials, dashboard software, analyst/CFO, data discipline | Ongoing performance visibility, early-warning indicators, management alignment | Growth-stage SMEs, investor reporting, operational management | Enables proactive decisions; standardises reporting; improves stakeholder communication |
| Accounting Records Quality and Internal Controls Assessment | Moderate–High | Bookkeeping records, system access, control specialist, IT controls | Reliable financials, fraud risk detection, process improvement recommendations | Preparing for audit, scaling businesses, outsourcing bookkeeping | Enhances reliability; reduces fraud risk; enables scalable operations |
From Checklist to Confidence Your Next Steps
A thorough financial due diligence checklist turns guesswork into informed judgment. It doesn't just protect a buyer from overpaying. It also helps a seller present the business properly, fix issues early, and keep the negotiation focused on facts rather than surprises. For UK SMEs using Xero and other cloud tools, that discipline matters even more, because the data is available in real time, but only if someone knows how to interrogate it properly.
The strongest deals usually come from the same habits. The buyer asks for the right records, tests them against the bank, tax, debtor, and creditor positions, and pushes beyond the headline profit. The seller cleans the ledger, documents the add-backs, and explains the unusual items before the other side spots them. That's where a proactive adviser adds value, not by making the process more dramatic, but by making it more usable.
Stewart Accounting Services works with SME owners who want straight answers, not jargon. If you're buying a business, preparing to sell one, or just want a proper review of your accounts before a lender or investor asks the hard questions, speak to a Chartered Accountant who understands UK SME deals and cloud accounting in practice. Contact Stewart Accounting Services to get your numbers tested properly, your risks identified early, and your next step mapped with more confidence.