
Segregation of Duties Guide for SMEs Practical Steps

A lot of small business owners already know something feels off in their finance process long before they call it a control problem. One person raises the supplier order, approves the bill, runs the payment, posts the entry, then ticks off the bank line at month end. It feels efficient until a duplicate payment slips through, a payroll change isn't spotted, or a director asks a fair question that nobody can answer cleanly.
That's where segregation of duties stops being theory and becomes practical protection. In an SME, the challenge isn't understanding the principle. It's making it work with a lean team, shared responsibilities and software that often gets set up once, then left alone.
Understanding the Key Concepts
A common trigger is a payroll mistake that sits in the system for months because the same person entered the pay change, processed the payroll, and reconciled the bank. Nothing malicious has to happen for the problem to become expensive. A control gap is enough.
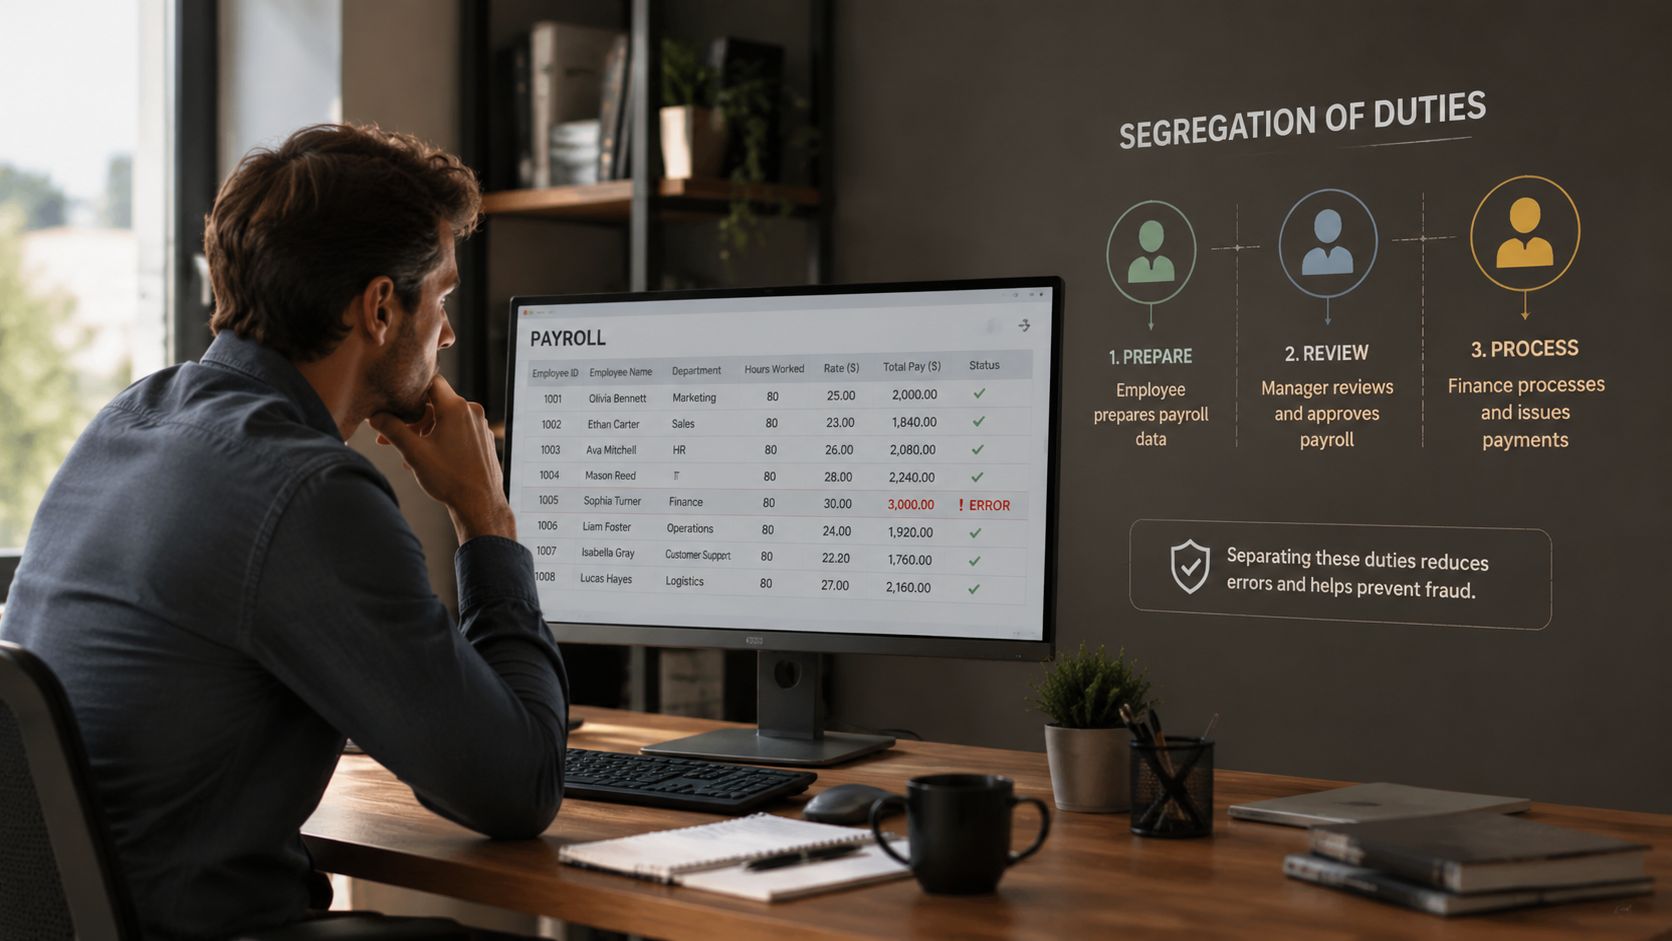
Segregation of duties means splitting key stages of a financial process so one person doesn't control the whole transaction from start to finish. In practice, the critical steps are usually initiation, approval, recording and reconciliation. If one person can do all four, they can make an error and hide it, or worse.
Why it matters in UK SMEs
In the UK, the principle isn't just good housekeeping. It sits inside the wider internal control expectations that directors are expected to take seriously. The Financial Reporting Council's Revised Code and the Companies Act 2006 reinforce the need for strong internal controls, and one source summarising that framework states that formal internal control frameworks can reduce fraudulent actions in SMEs by an estimated 40 to 60% (dynamicshub.co.uk).
That matters to owner-managed businesses because the weakest point is often convenience. The same trusted employee, or the owner, does “a bit of everything”. That may keep work moving, but it also removes the independent check that catches problems early.
Practical rule: If the same person can create, approve and then clear a transaction, you don't have a process. You have trust standing in for control.
The day-to-day consequence is simple. The person handling payroll shouldn't also be the final reviewer of the bank effect. The person creating a supplier payment batch shouldn't be the same person approving it. If a business can't split those roles physically, it needs another control that's visible, documented and effectively performed.
What good looks like
For smaller firms, strong segregation of duties doesn't mean building a corporate bureaucracy. It means deciding where independent review has to happen and proving that it happened. That's often part of optimizing your financial accounting workflows, especially when cloud systems have grown faster than internal discipline.
A workable mindset is this:
- Separate the money movement from the approval
- Separate data entry from review
- Separate reconciliations from the original posting
- Document any exception where one person has to cover two roles
Those four habits do more than tidy up finance. They make audits easier, reduce avoidable disputes, and help directors show they've exercised proper oversight.
Mapping Financial Workflows and Conflict Risks
Most SMEs don't need a long policy document before they improve segregation of duties. They need a map of what occurs. Start with routine workflows, not edge cases. Purchasing, payroll, expenses, bank reconciliation and journals are where conflicts usually hide.
Where duties collide
The first pass should be brutally practical. Write down each task and the name of the person doing it. Then ask a narrow question. Does the same person also approve, record or reconcile that task later in the cycle?
Here's a simple way to spot the clashes.
| Finance Task | Conflict Risk |
|---|---|
| Raising a purchase order | High risk if the same person also approves supplier selection or authorises payment |
| Setting up a new supplier | High risk if that person can also process or approve vendor payments |
| Entering supplier bills | Risk increases if the same user also reconciles the creditor balance |
| Processing payroll changes | Problematic if the same person runs payroll and checks the bank impact |
| Submitting expense claims | Weak control if the claimant approves their own claim or posts reimbursement |
| Posting journals | Higher risk when the same person reviews the reports affected by those journals |
| Taking cash or handling stock | Conflict if custody of assets sits with the same person doing record-keeping |
| Reconciling the bank | Poor practice if the reconciler also created or approved the payments being matched |
This isn't about assuming dishonesty. It's about identifying combinations that remove challenge.
The high-risk combinations to check first
In smaller teams, a few pairings matter more than others:
- Supplier setup and payment approval create obvious exposure if left with one user
- Payroll amendments and bank reconciliation can let errors sit unchallenged
- Expense submission and approval weaken discipline quickly, especially for directors
- Journal posting and report review can distort management information without a second set of eyes
If payables are a regular pain point, it helps to review the underlying process as well. A clear explanation of accounts payable management can help owners see where approval, recording and payment tasks drift together over time.
The best workflow maps are short enough to use. If your team won't look at it during a busy week, it's too complicated.
A simple mapping method
Use one sheet and keep it visible. For each workflow, note:
- Who starts the transaction
- Who approves it
- Who records it in Xero or another system
- Who reconciles or reviews the final outcome
Once that's done, conflicts usually stand out without much debate. The goal isn't perfection on day one. The goal is knowing exactly where your business depends on one person doing too much unchecked.
Implementing Segregation of Duties Controls
Once the weak spots are visible, the next step is building controls that a small team can sustain. In businesses with fewer than 15 staff, the practical route is often compensating controls rather than perfect role separation. One cited UK summary describes the working approach as mapping workflows, enhancing audit logging for finance actions, and mandating manager reviews for exceptions, with unreviewed exceptions identified as the leading precursor to fraud in small entities (hightable.io).
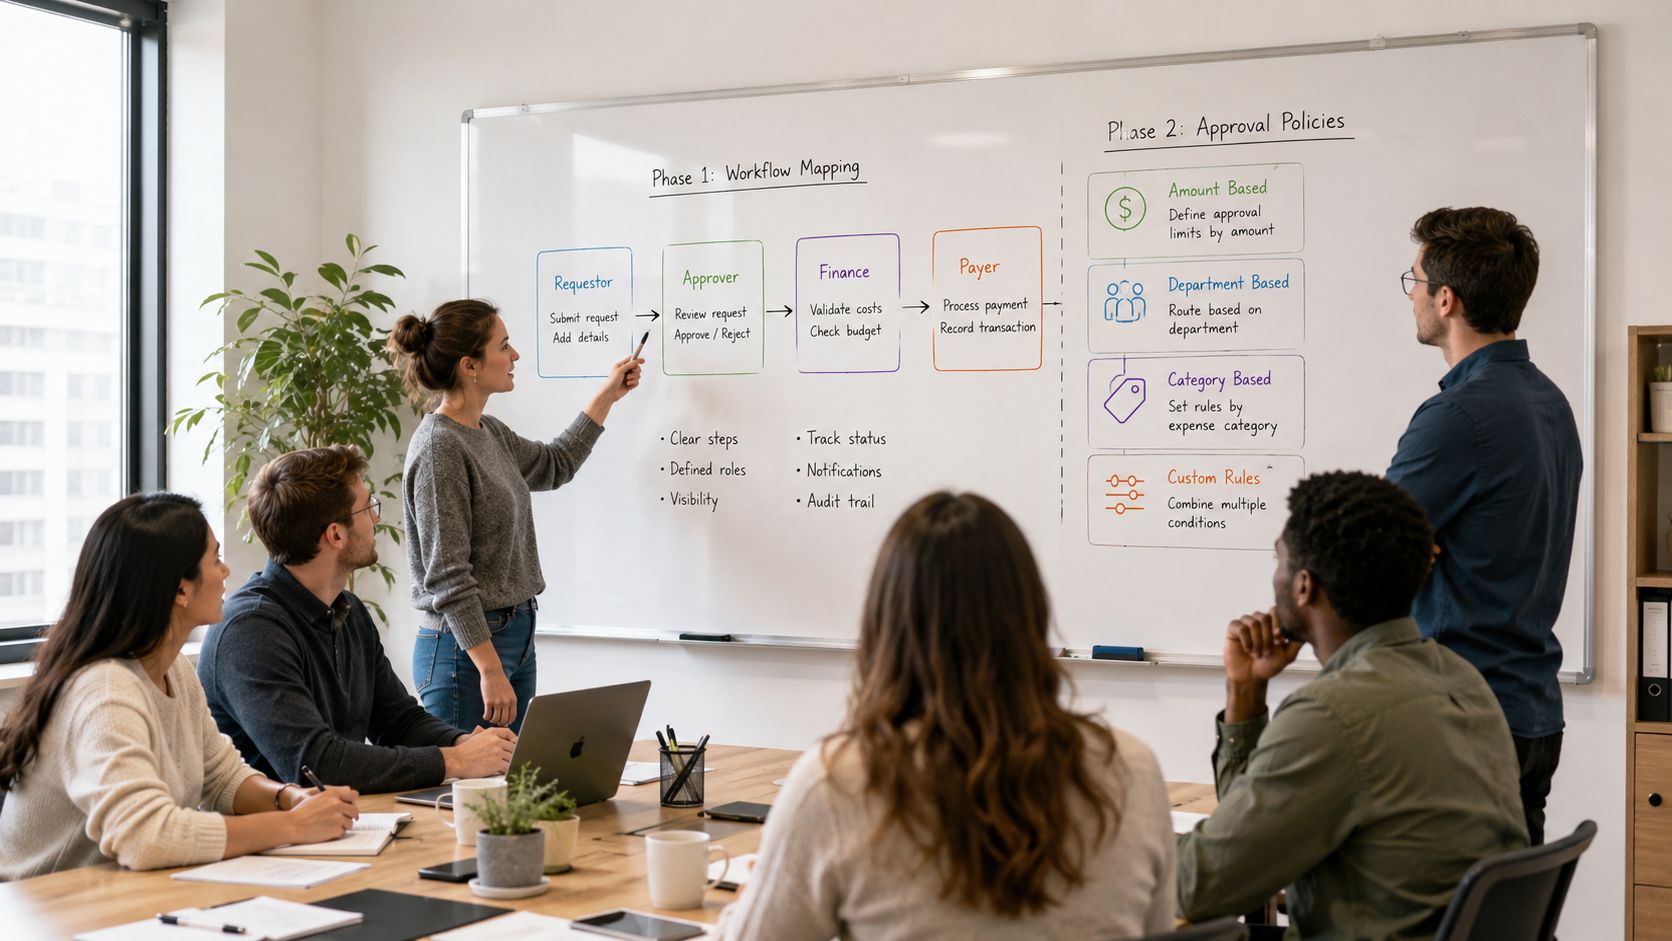
Phase one around roles and workflows
Start by assigning each finance activity to a named role, even if one person currently holds several. That distinction matters because it shows what should happen, not just what currently happens.
The seven incompatible duties that deserve close attention are:
- Initiating transactions
- Approving transactions
- Approving supplier selection
- Recording transactions
- Reconciling balances
- Handling assets
- Reviewing reports
If your business can't separate all of them, don't hide the overlap. Record it.
Phase two around policies and approvals
Small firms often overcomplicate things. You don't need a bulky manual. You need a few hard rules that people can follow every week.
A sensible minimum includes:
- Approval limits: Who can approve bills, payroll changes, expenses and ad hoc payments
- Bank reconciliation ownership: The reconciler shouldn't be the person who made the payment run
- Supplier changes: New suppliers and bank detail changes should be reviewed independently
- Journal discipline: Non-routine journals need a reviewer, especially if they affect payroll, VAT or director accounts
What works: short written rules tied to actual tasks in Xero, payroll software and online banking.
What doesn't: a policy file nobody opens, while permissions in the system tell a different story.
Phase three around compensating controls
Small teams will encounter staffing limits. Holidays, sickness and growth stages all create temporary overlap. When that happens, use compensating controls that leave evidence.
A strong exception record should show:
- Owner: who carried out the conflicting duties
- Reason: why the exception happened
- Review date: when management checked it
- Evidence of oversight: what was reviewed, by whom, and where that evidence sits
Detailed supervisory review is usually the right answer when you can't physically split the work. The review needs to be real. That means looking at source documents, approvals, change logs and reconciliations, not just signing off because the figures “look about right”.
If you want segregation of duties to survive contact with a busy month end, build it into recurring routines. Weekly payment review. Monthly payroll check. Scheduled balance sheet review. Controls fail when they depend on memory.
Configuring Cloud Accounting Tools
Software won't create segregation of duties on its own, but poor setup can wipe out good intentions. That's especially true in Xero and similar cloud platforms, where businesses often give broad access early on and never revisit it.
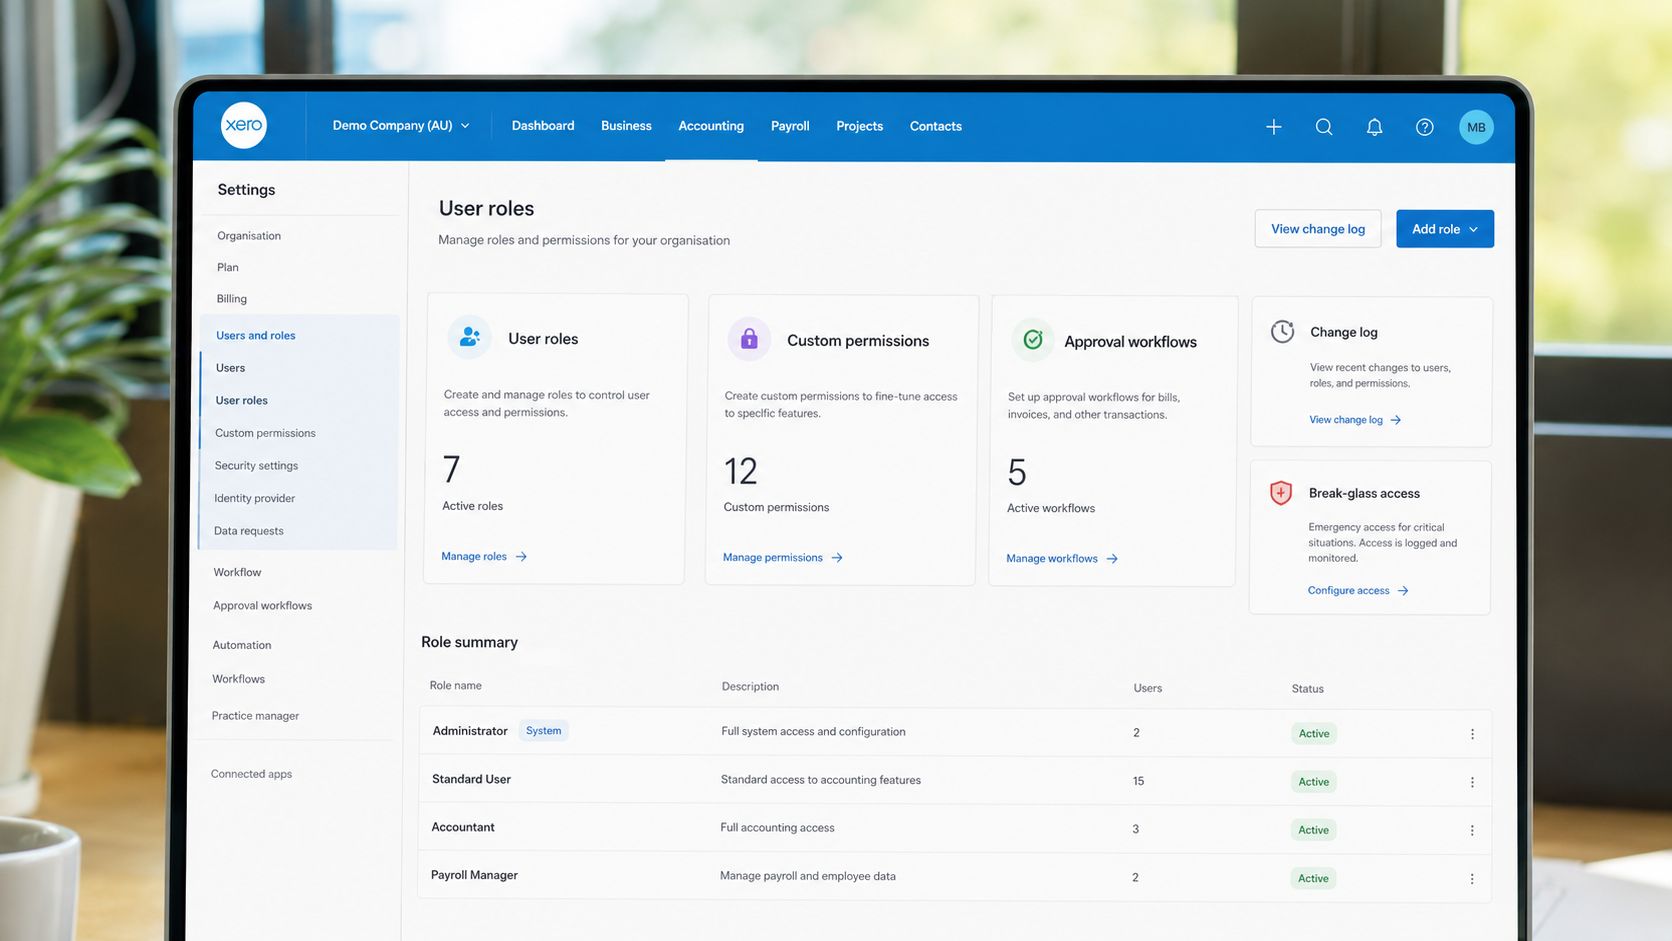
One source summarising SoD practice reports that organisations with strong frameworks detect fraud 50% faster than those without, and warns that over-reliance on manual matrices instead of automated role-based access control and emergency access protocols can leave a 30 to 40% gap in audit evidence (patrickcannon.net).
Set roles by task, not by seniority
A common mistake is giving someone broad access because they're trusted or because they're “in finance”. Access should follow duties, not job title.
In Xero, that usually means reviewing:
- Bills and purchase access
- Bank reconciliation access
- Payroll visibility and payroll processing rights
- Report access
- User management rights
- Advisor or admin-level permissions
If a user can enter bills, approve payment decisions outside the system, and reconcile the bank, you've probably recreated the same conflict digitally.
For firms moving more processes online, cloud accounting for small business only works properly when user permissions are part of the implementation, not an afterthought.
Build an approval trail you can defend
Good cloud control design creates evidence without extra drama. Focus on settings that show who did what and when.
Use this checklist inside your platform and connected apps:
- Limit user rights: Give the lowest level of access that still lets the person do their job
- Turn on change visibility: Keep audit history active and review it for sensitive actions
- Separate app ownership: Don't let one user control bookkeeping, payroll app settings and payment tools without oversight
- Review user lists regularly: Remove old users, dormant logins and temporary access that was never withdrawn
This walkthrough is useful if you want to see role and permission concepts in action before adjusting your own setup:
Handle emergency access properly
Every small business has moments where someone needs temporary increased access. A payroll manager is off sick. A director needs urgent visibility. A bookkeeper needs to fix a blocked payment process. That isn't the problem. The problem is leaving that access in place afterwards.
Keep emergency access controlled with three rules:
- Document why it was granted
- Limit how long it stays active
- Review the activity after the event
That post-event review is where many SMEs fall short. If emergency access is invisible or undocumented, audit readiness weakens quickly.
Real-World Scenarios and Practical Tips
The most useful segregation of duties designs are usually quiet. They don't slow the business down much, but they stop one person from operating unchecked.
A property landlord using outsourced bookkeeping is a good example. The landlord approves major spend and confirms new supplier details, while the bookkeeper records invoices and prepares the bank reconciliation. That split is simple, but effective. The owner stays in control of commitment and payment intent, while the records are kept by someone else.
A contractor running payroll through Xero often needs a different setup. The payroll input might still come from one person, but the approval of pay changes and the review of the bank effect should sit elsewhere. If staffing is too tight, a documented monthly supervisory review can still create a credible check.
Keep controls lean. If the process adds friction but no independent challenge, it's admin, not control.
Another useful discipline in purchasing is invoice matching. If you want a straightforward explanation of why purchase orders, goods received and invoices should line up, Doczen explains three-way matching effectiveness in a way that fits smaller finance teams as well as larger ones.
Five practical tips tend to hold up well in SMEs:
- Start with payment workflows: Supplier payments and payroll create the most obvious risk when duties overlap
- Use named reviewers: “Management review” is vague. Name the director or manager who checks the exception
- Treat supplier bank detail changes as high risk: They deserve a second check every time
- Make reconciliations independent where possible: Even a short review by another person is better than none
- Revisit permissions after staff changes: Promotions, leavers and temporary cover often create hidden conflicts
Good segregation of duties is rarely elegant on paper in a small firm. It just needs to be clear, repeatable and evidenced.
Conclusion and Audit-Ready Checklist
Segregation of duties isn't about making a small business behave like a large corporate. It's about stopping avoidable errors, exposing unusual activity sooner, and showing that directors have applied sensible oversight. The strongest SME control frameworks are usually the simplest ones. Clear roles, clean approvals, visible exceptions and a review habit that doesn't slip when the month gets busy.
If you already manage regulated workflows elsewhere in the business, it can help to compare your finance controls with other structured compliance checklists. For example, guidance on how to achieve PCI DSS compliance with actionable steps shows the same broader principle. Document responsibilities, restrict access and keep evidence.
Use this audit-ready checklist before your next review:
- Define roles clearly: Identify who initiates, approves, records and reconciles each key workflow
- Record conflicts openly: Log every exception where one person covers more than one critical duty
- Set system permissions properly: Match Xero and connected app access to real responsibilities
- Keep approval evidence: Retain support for payroll changes, supplier setup, expenses and payment runs
- Review exception logs regularly: Make sure each exception shows owner, reason, review date and oversight evidence
- Check your audit history: A reliable audit trail makes control reviews far easier
- Schedule recurring oversight: Put monthly and weekly reviews in the diary so they happen consistently
If you want help designing segregation of duties that fits a growing SME without turning finance into a bottleneck, Stewart Accounting Services can help you build practical controls around bookkeeping, payroll, VAT, reporting and cloud accounting workflows.