
Limited Company Accounts Cost in the UK: Typical Ranges
For a simple micro company with clean records, the annual professional fee depends on the work required, so request an itemised quote rather than relying on a headline figure. Preparing accounts from reconciled records takes different work from reconstructing missing transactions, and that difference can affect the fee.
Budget for the full cost of accurate accounts and tax information being prepared, reviewed and submitted, not just the quoted compliance fee. Include any separate bookkeeping, software or tax work, along with the time you spend supplying records and addressing corrections.
A low headline quote can still represent good value if its scope fits your company. Before signing, check exactly what is included and what would be charged separately. Your workload and record-keeping provide a more useful basis for comparing quotes than an unsupported market average.
Typical Limited Company Accounts Costs by Profile
Professional fees aren't statutory tariffs. A contractor buying year-end compliance and a trading business outsourcing its finance administration aren't purchasing the same service, even if both describe it as accounts.
There's no defensible government-sourced annual accountant fee range for these profiles. Rather than presenting an unverified price band as a market fact, use the packages below to establish the annual budget you need quoted.
Before requesting a price, describe your business clearly:
- People: Identify the directors and employees, including anyone paid through payroll.
- Activity: Export your transaction history, including bank accounts, payment processors and company credit cards.
- VAT: Explain your registration position and whether you need return preparation.
- Structure: Disclose stock, related companies and separate trading activities.
Indicative annual cost by profile and package
| Profile | Package | Typical annual cost | Main cost drivers |
|---|---|---|---|
| Contractor, one director, low transaction volume, no staff | Year-end accounts and Company Tax Return | Itemised compliance quote required | Director's loan account, expenses |
| Owner-managed trading company, several directors, VAT registered | Compliance plus bookkeeping | Combined annual service quote required | Recurring bookkeeping, VAT returns |
| Growing SME with staff and high transaction volume | Compliance, payroll and VAT | Workload-based package quote required | Payroll, stock, several bank accounts |
| Multi-million-pound company with group structure | Full advisory package | Bespoke group quote required | Group tax, stock, directors' loans |
Set a budget you can actually test
For a contractor, test the price of accounts and tax compliance from complete records. Keep bookkeeping support, software and personal tax work identifiable rather than assuming they're bundled into the company fee.
For an owner-managed trading company, request an annual total that includes the recurring work you want delegated. A compliance-only quote isn't a usable budget if nobody has priced the bookkeeping or VAT preparation.
A growing SME needs a broader test. Establish who will maintain the purchase ledger, reconcile payment processors, provide payroll information and resolve stock discrepancies. Otherwise, the accountant and your internal team may each assume the other is doing the preparation.
For a group, provide an organisation chart and explain intercompany activity before discussing price. Turnover alone doesn't describe the accounting work.
Budget rule: Compare complete annual packages for the same responsibilities, not isolated monthly payments.
We assist contractors and freelancers trading through limited companies, and our client base extends from tax-return-only clients to companies turning over multi-million-pound amounts. That breadth makes a clearly defined scope more useful than a single advertised starting price.
Choose your closest profile and obtain a written annual quote for that package. Keep Companies House administration charges separate from professional fees so you can see what you're paying the accountant to do.
What Drives the Price Up or Down
Your accountant isn't just transferring a bank balance into a filing form. The work connects bookkeeping records, statutory accounts and the company's tax position.
Under HMRC's Company Tax Return guidance, accounts and tax computations accompany the electronic return in iXBRL format; the return is due 12 months after the accounting period ends, while Corporation Tax is generally payable at 9 months and 1 day.
That gap matters. A service organised only around the return deadline may not provide the tax information you need when payment falls due. Your quote should describe the preparation timetable, not just promise eventual submission.
The preparation work starts with reviewing the underlying records.
Cost drivers: lower-cost and higher-cost states
| Factor | Lower-cost state | Higher-cost state |
|---|---|---|
| Bookkeeping quality | Software current and bank accounts reconciled | Receipts and statements needing reconstruction |
| Transaction volume | Few, straightforward transactions | High volumes across several payment channels |
| Payroll | No payroll, or straightforward director pay | Several employees and payroll changes |
| VAT | Not registered | Multiple rates or partial exemption |
| Stock and fixed assets | No stock and few assets | Stock counts, purchases and disposals |
| Directors' loans | Clear, supported balance | Overdrawn account requiring tax review |
| Trading structure | Single entity and activity | Group structure or several trading streams |
Why similar turnover can produce different quotes
Consider a consultant paid by bank transfer and a retailer receiving card payments, marketplace settlements and cash. Even with similar revenue, the retailer's accountant must reconcile more sources and distinguish sales, fees, refunds and settlement timing.
Transaction volume and transaction complexity are different cost drivers. Repeated, consistently coded transactions may be easier to review than a smaller collection of unexplained transfers. Software helps organise the records, but someone still needs to resolve discrepancies.
Stock and fixed assets introduce another kind of work. The accountant needs reliable information about what remains on hand, what was purchased and what was sold or disposed of. A bank statement alone won't answer those questions.
Directors' loans require particular care. Say a director regularly uses the company account for personal spending. The accountant must establish the balance, understand repayments and assess the tax treatment, rather than treating every outgoing as a business expense.
The practical pricing lever is readiness for review. Provide reconciled balances, supporting documents and explanations for unusual transactions. Ask the accountant to identify what preparation you can take over without taking responsibility for technical accounting judgements.
Statutory Fees and Late-Filing Penalties
There isn't a single government price for getting your company's accounts done. The Companies House fees schedule separates service charges and explains its cost-recovery approach; it lists digital confirmation-statement filing at £50 from 1 February 2026.
The corresponding paper confirmation-statement fee is £110 from 1 February 2026, according to Companies House's online-filing guidance. These are confirmation-statement charges, not annual accounts preparation fees.
Your professional bill may include preparing a submission, while the statutory charge remains separately payable. An inclusive-looking package therefore needs an explicit statement about disbursements.
The larger exposure is missing the deadline
The government's accounts-filing guidance gives private companies a general deadline of 9 months after the accounting reference date, with the following late-filing penalties; it also identifies failure to deliver acceptable accounts on time as a criminal offence.
Late-filing penalties for private companies
| Delay past deadline | Penalty |
|---|---|
| Up to 1 month | £150 |
| More than 1 month, up to 3 months | £375 |
| More than 3 months, up to 6 months | £750 |
| More than 6 months | £1,500 |
These aren't discretionary additions to an accountant's invoice. Companies House's late-filing penalty guidance explains that penalties are automatic, separate from HMRC penalties, and double when accounts are filed late in successive financial years.
A low preparation fee doesn't protect you against those consequences. Nor does appointing an accountant remove the need to provide records and approve the accounts in time.
A deadline-management service has financial value only when the accountant and director both know what must happen before submission.
Compare the process behind the price
Consider a hypothetical cheap package that leaves record collection until the filing deadline approaches. If the accountant then discovers missing statements or an unexplained director's loan, you may face urgent preparation work as well as filing risk.
A more expensive package could be better value if it includes earlier review and a clear schedule for resolving queries. That isn't a guarantee that higher fees produce better outcomes. It's a reason to assess the process instead of using price as a proxy for quality.
Our guide to the Companies House late-filing penalty explains the consequences in more detail. Before signing, establish who monitors the reference date, when records must arrive, who approves the accounts and how late information will be handled.
DIY Versus Outsourced Accounting Compared
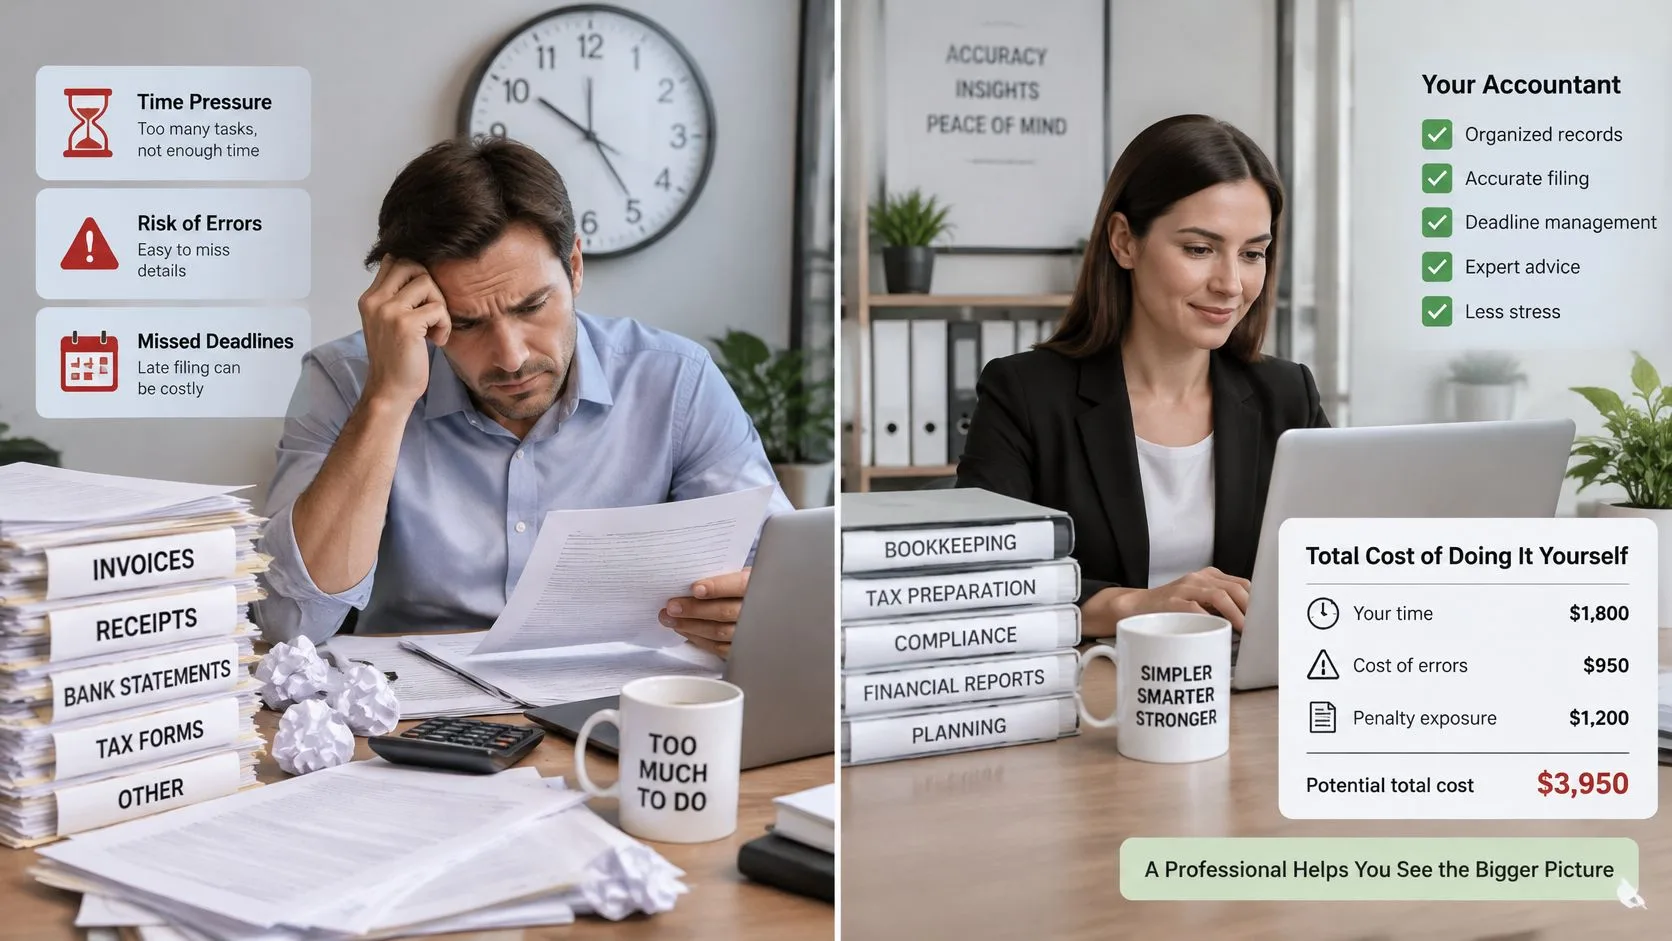
Doing your own bookkeeping and preparing your own statutory filings are different decisions. You might be comfortable categorising purchases in Xero while still wanting professional review of the accounts and tax computation.
Compare the work you'll retain, not whether an accountant appears on the supplier list.
Doing it yourself versus outsourcing
| Criterion | Doing it yourself | Outsourced to an accountant |
|---|---|---|
| Direct cost | Software and any technical support you purchase | Agreed professional fee and identified extras |
| Owner time | Preparation, technical checks and submission | Record provision, answering queries and approval |
| Error risk | You identify and resolve accounting and tax issues | Professional review within the agreed scope |
| Deadline management | You maintain the timetable | Accountant monitors agreed deadlines |
| Penalty exposure | Company remains exposed if filing is late | Company still exposed if the process fails |
| Hidden costs | Rework and time away from running the business | Extra work outside an unclear engagement |
Put a value on your retained workload
A straightforward service company may be able to maintain its own records efficiently. That doesn't mean cloud software will make every accounting or tax decision for its director.
For example, a correctly reconciled bank account can still contain incorrectly classified personal expenditure. The arithmetic may balance while the accounts and tax treatment need correction.
Value your time using your own realistic hourly opportunity cost, not a generic director's rate. Include collecting documents, learning the filing process, investigating differences and correcting rejected or inaccurate work.
Don't automatically assume every hour saved becomes extra revenue. The relevant benefit may instead be protecting time for customer delivery, staff management or overdue operational decisions.
The accompanying video offers another way to consider the filing decision.
Keep the useful work in-house
A hybrid arrangement can separate routine bookkeeping from technical year-end work. You maintain the records, while the accountant prepares and reviews the statutory accounts and Company Tax Return.
We work with Xero and other leading cloud accounting software, whether clients are established users or have recently switched. We also set up Xero and supporting apps so clients can manage their own bookkeeping more efficiently.
The right split depends on your skills and capacity, not just company size. An owner who understands the software but never has time to use it needs a different arrangement from one who keeps accurate records throughout the year.
Use our guide to filing limited company accounts yourself or using an accountant to assess the responsibilities you'd retain. Outsourcing works best when you delegate a defined task rather than assuming the accountant will discover every unfinished job.
Cost-Saving Tips That Keep Compliance Intact
Reduce the work that doesn't require professional judgement. That's a safer approach than removing review or choosing a package that leaves necessary tasks unassigned.
The aim is to make your records easier to use and your engagement easier to price.
Build a repeatable records routine
- Reconcile bank feeds regularly: In Xero, match transactions to invoices, bills and receipts, then compare the reconciled balance with the bank statement. A live feed isn't evidence that everything has been categorised correctly.
- Share documents as you go: Upload purchase invoices and receipts when you receive them. Add a note explaining unusual expenditure while you still remember its business purpose.
- Review the director's loan account: Identify personal spending, money introduced and repayments before the year-end review. Discuss an overdrawn balance with your accountant before moving money or relabelling transactions.
Don't delete an unexplained entry to make the reconciliation work. Keep a query list with the transaction date, supplier, amount and missing explanation so the accountant can resolve the actual issue.
Documenting a director's loan balance doesn't itself remove a possible tax charge. The saving comes from making the facts available early enough for proper advice, not from changing a bookkeeping description.
Practical rule: Resolve uncertainty while the people involved can still explain the transaction.
Control extras without cutting necessary work
Agree a fixed fee for a defined scope. We offer guaranteed fixed fees linked to the value of what we provide. For a useful comparison, the engagement still needs to distinguish recurring services from separately commissioned work.
Tell the accountant when your business changes. Hiring staff, introducing stock or adding a payment platform can alter the workload, so discuss the revised scope before assuming the original arrangement still fits.
Keep your own compliance calendar. Record the information handover, query-resolution and approval dates, not merely the final submission date. Assign someone inside the company to respond when the accountant requests missing information.
A smaller company can keep this process simple. A shared document folder, a maintained query list and a recurring bookkeeping appointment may be sufficient operational tools. A business with delegated finance duties should also name who owns each task.
These habits won't guarantee a lower quote, because technical complexity may remain unchanged. They do give you a stronger basis for asking what work the fee covers and which avoidable preparation tasks you can remove.
Get an Itemised Quote Before You Commit
An itemised quote should let you understand the annual commitment without guessing what the accountant meant by accounts. It should also explain the boundaries of the service when something changes.
Use the following questions as an acceptance checklist rather than treating the headline fee as the decision.
What exactly will you prepare and submit?
Request separate descriptions of statutory accounts, the Company Tax Return, tax computations and electronic filing. Identify bookkeeping clean-up, software, VAT, payroll and personal tax work explicitly.
A reference to tax support is too broad to establish whether it covers a routine query, planning advice or an enquiry. Specify the service you need.
What changes the agreed fee?
Check whether the quote is fixed or variable and how additional work is authorised. Read the terms of business alongside the engagement scope rather than relying on a sales conversation.
Useful distinctions include ordinary year-end adjustments versus reconstructing missing records, and routine support versus a separately commissioned advisory project. Ask for those distinctions in writing.
Who owns each deadline and approval?
Confirm who collects records, answers queries, reviews drafts and authorises submission. The engagement should explain the consequences of late information and how responsibility for any resulting penalty is assessed.
Don't accept an assumption that reminders alone constitute complete deadline management. Your internal responsibilities must be workable too.
Does the price cover filing changes?
The government's accounts-filing guidance states that the joint online accounts and Company Tax Return service closed on 31 March 2026, and describes planned reforms from April 2028 requiring small companies and micro-entities to file profit-and-loss accounts, with an option not to make those figures public.
Separate the stated service closure from the planned reforms. Filing information and publishing it publicly aren't the same decision, and planned requirements shouldn't be treated as though they already apply.
Ask whether the package includes compatible commercial software, tagging, transition work and any additional presentation or review. Your professional fee could change even if your tax bill doesn't, because the accountant's preparation work may change.
Are administration and advice priced separately?
Identify Companies House submissions, HMRC filing and advisory time on separate scope lines. You can then compare equivalent packages and decide which support to retain internally.
The best price is the price for a complete, workable allocation of responsibilities. An inexpensive package can be right for a well-organised company; a broader package can be right when the director needs recurring support.
Request an itemised quote from Stewart Accounting Services using your business profile, current records and required services. Our initial consultation visit is without charge. Bring your existing fee breakdown, software details and outstanding bookkeeping queries so we can discuss a defined fixed-fee scope and the work you'll keep in-house.
Recent Posts
07 Nov, 2026